A complete GC-400 account, schedule by schedule
This is a complete sample standard account for a fictional conservatorship, the Conservatorship of the Estate of Eleanor R. Pratt, generated by Balanced in the layout of the Judicial Council’s GC-400 forms: six months, a bank account and the conservatee’s residence. The conservatorship, the people and the account numbers are made up. Schedules with no entries are left out, as the Summary of Account directs. Click any schedule to see the whole sheet.
Download the sample accounting (PDF)
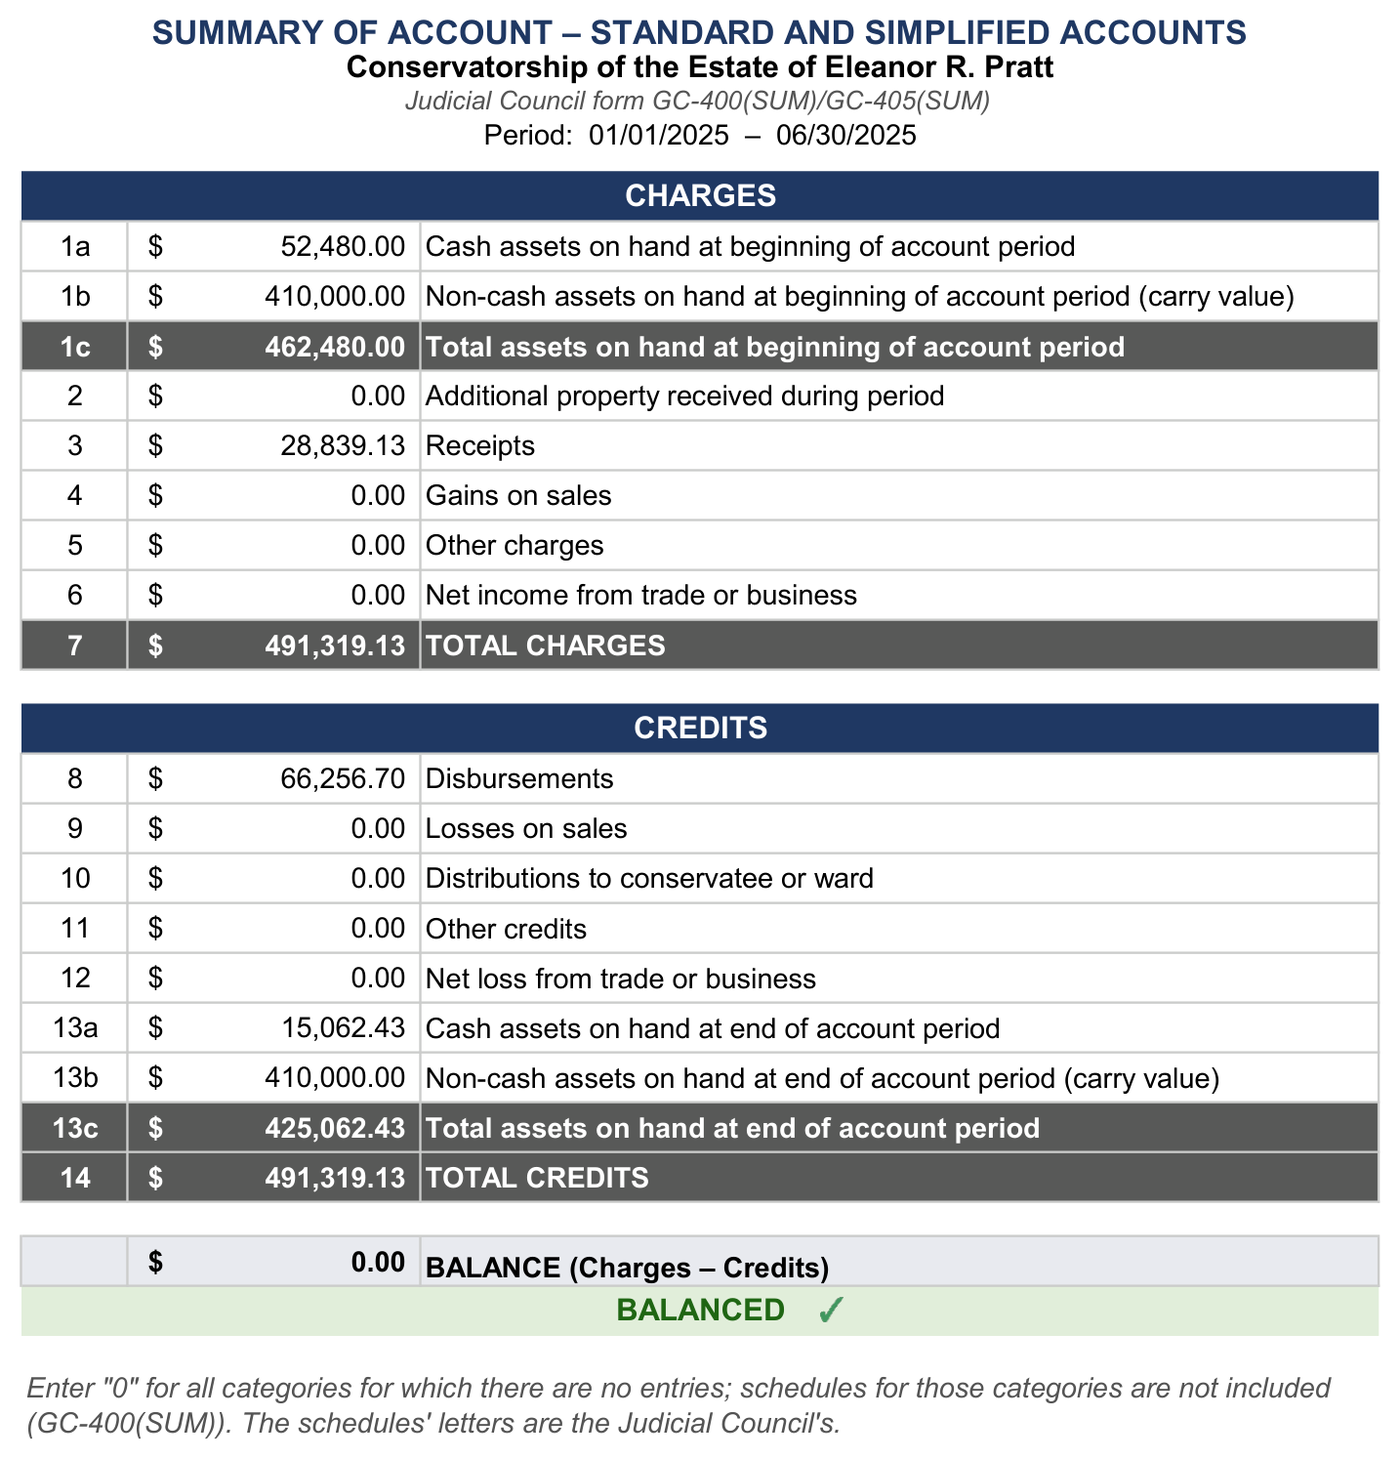
Summary of Account, GC-400(SUM)
The Judicial Council’s Summary of Account, line by line: cash and non-cash assets at the beginning, receipts, gains, disbursements, losses, distributions, and cash and non-cash assets at the end. Total charges equal total credits.
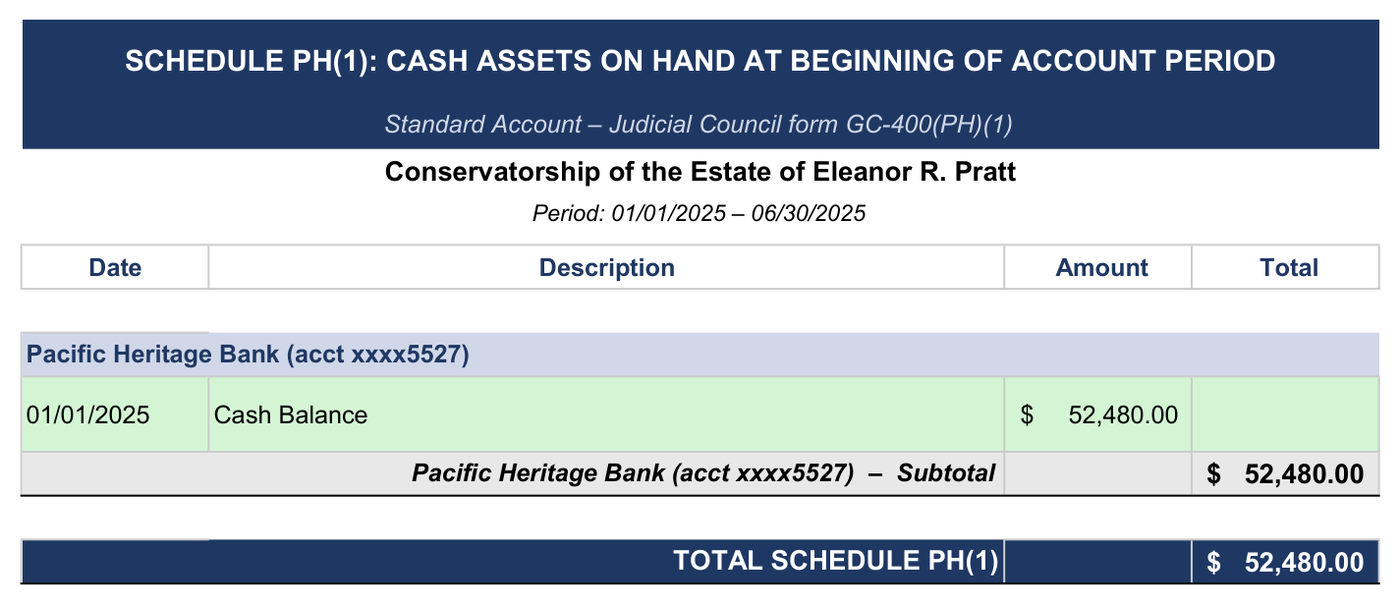
GC-400(PH)(1): cash assets on hand at the beginning
Each account’s cash balance on the first day of the period.
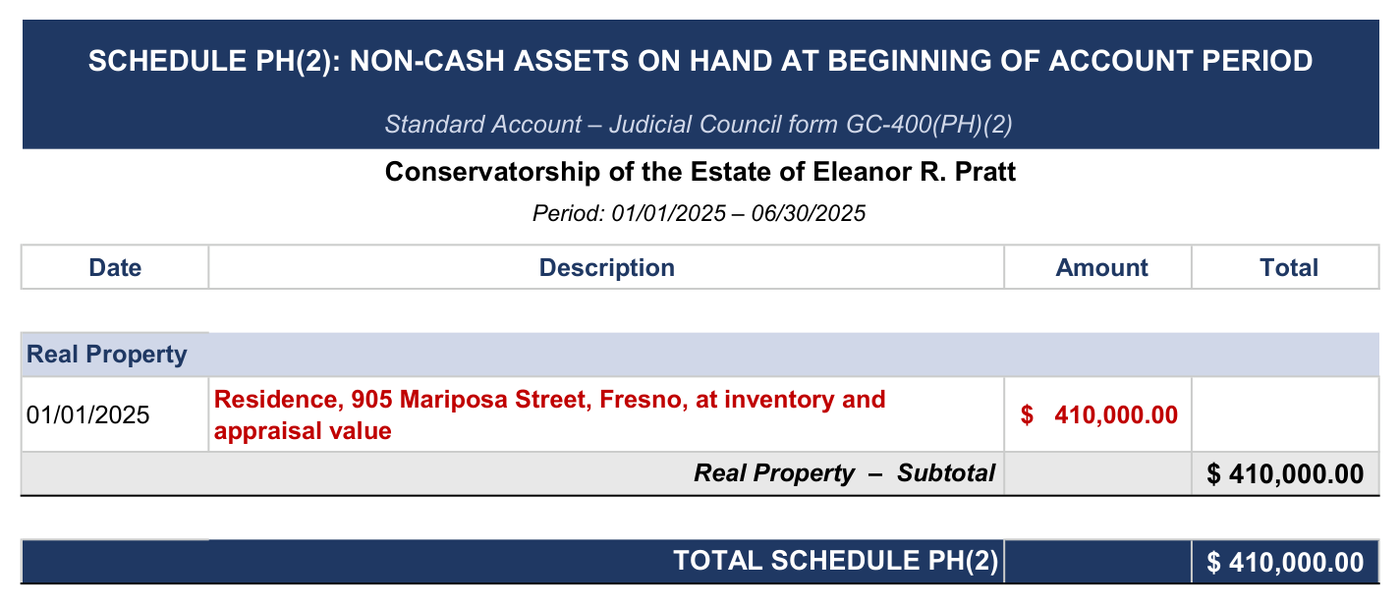
GC-400(PH)(2): non-cash assets on hand at the beginning
Non-cash assets, such as the residence, at carry value, with estimated market value.
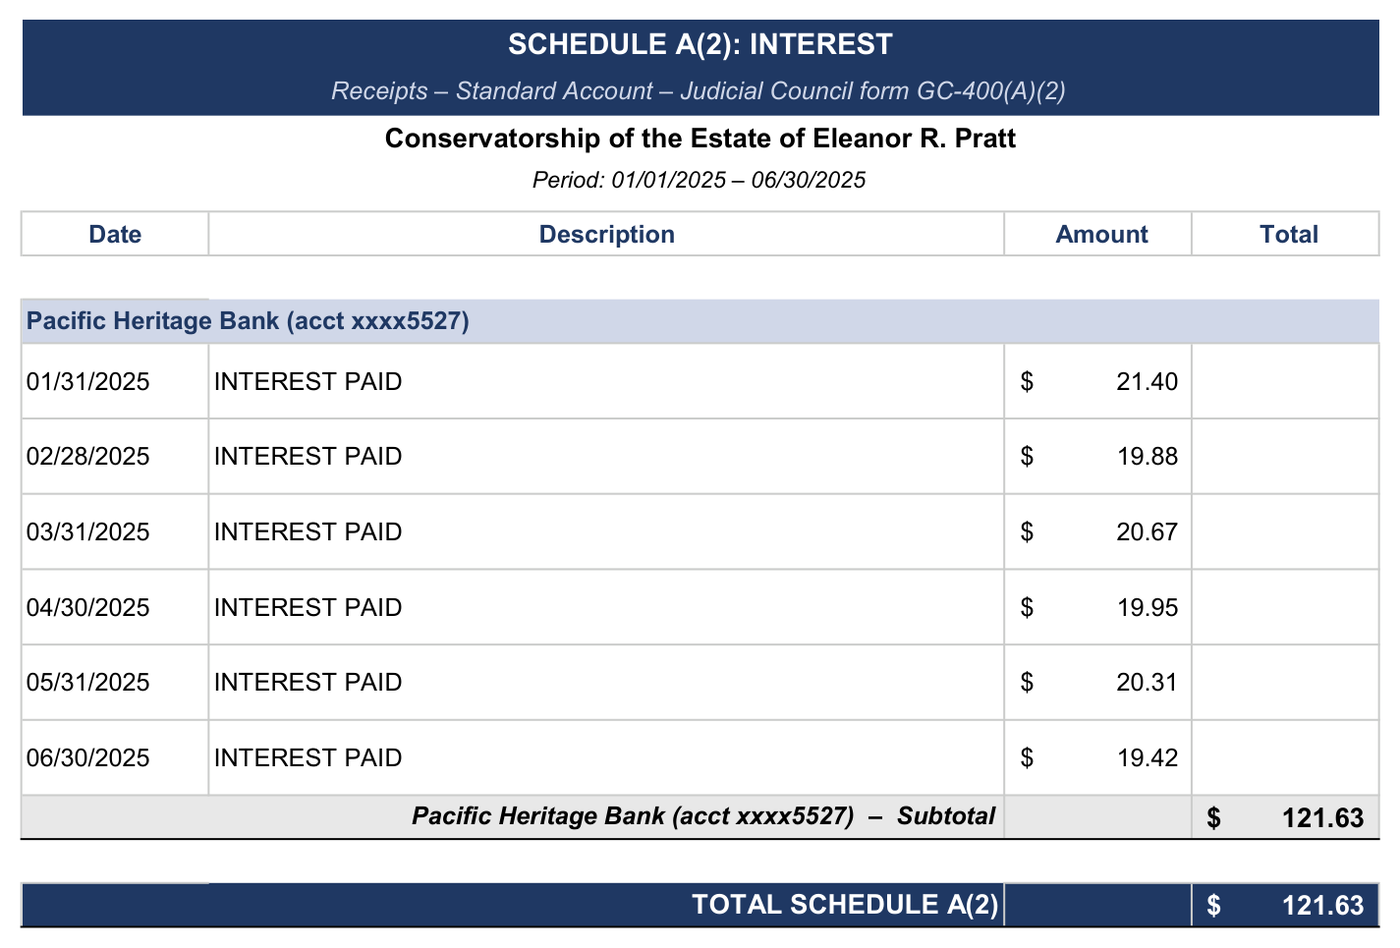
GC-400(A)(2): interest
Each interest payment received.
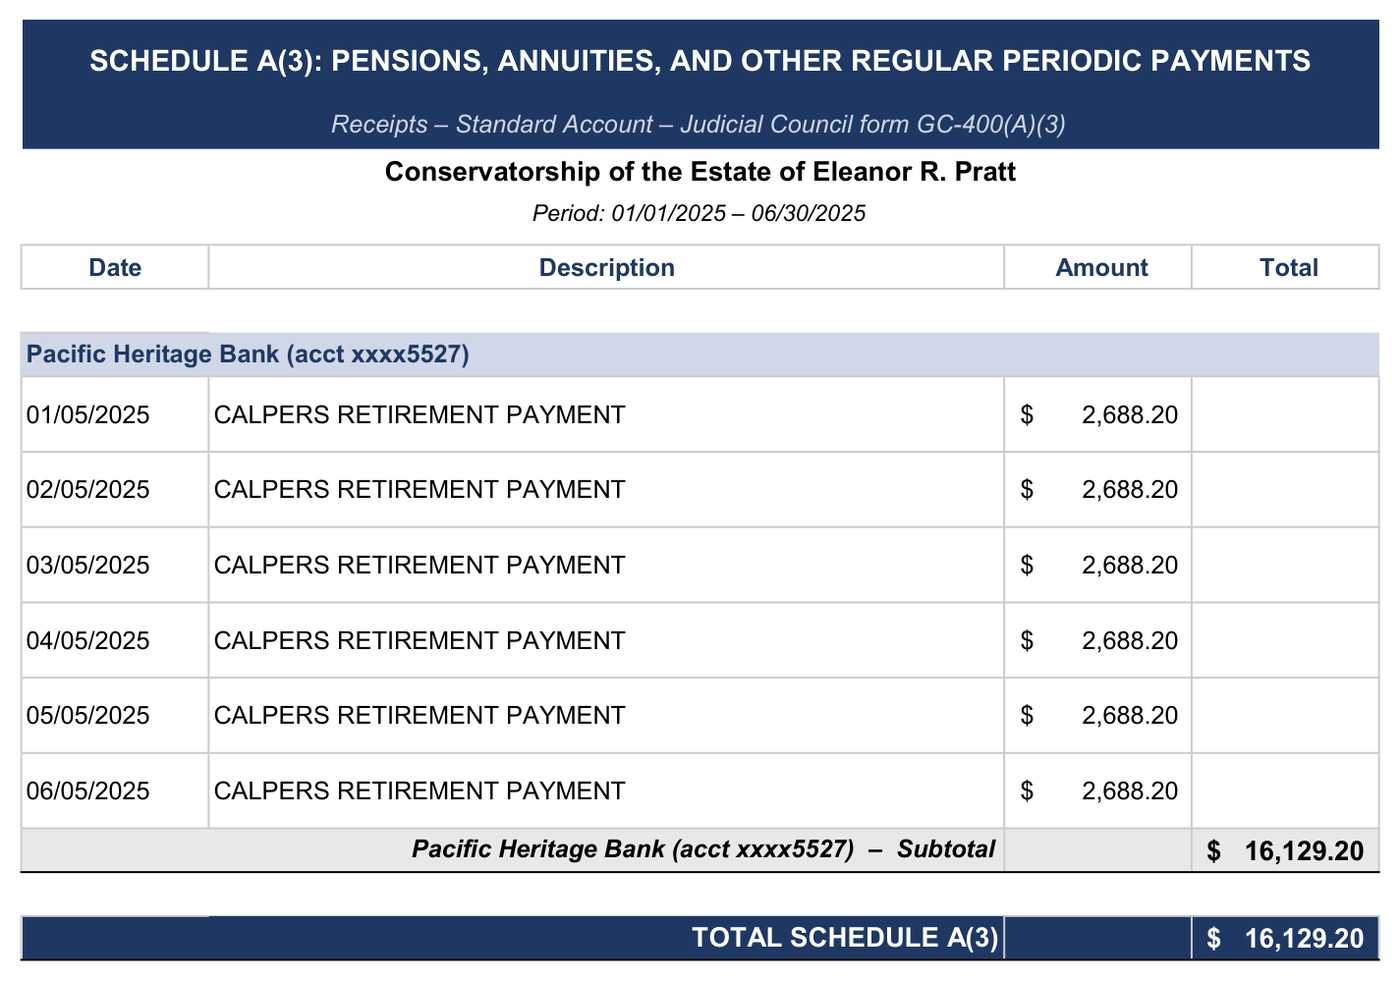
GC-400(A)(3): pensions, annuities and retirement income
Each pension, annuity and retirement payment received.
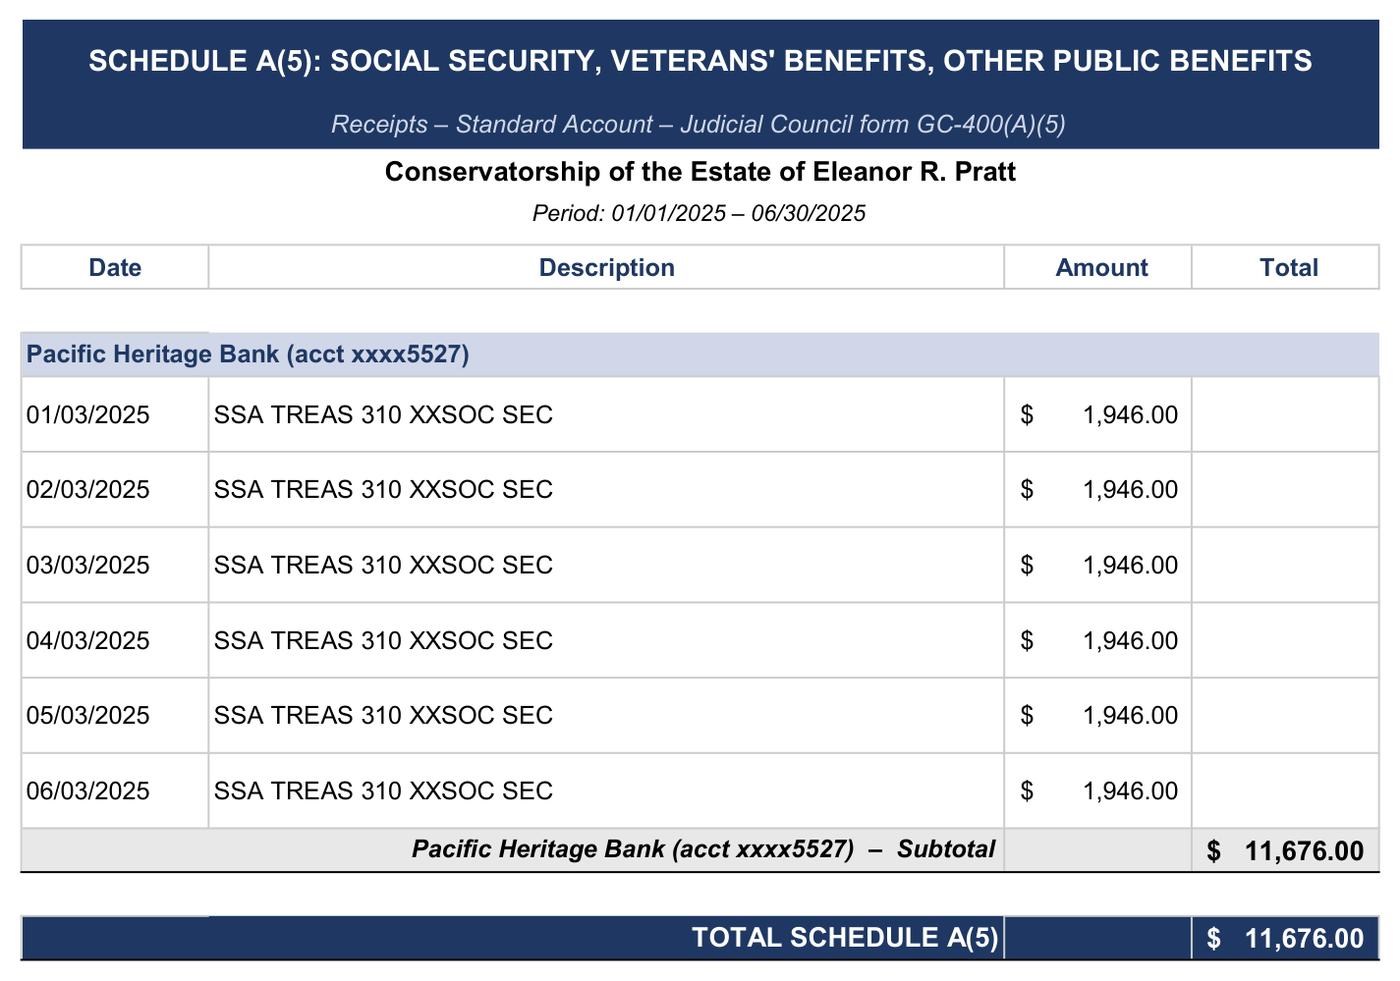
GC-400(A)(5): Social Security and other public benefits
Each Social Security, veterans’ and other public benefit payment received.
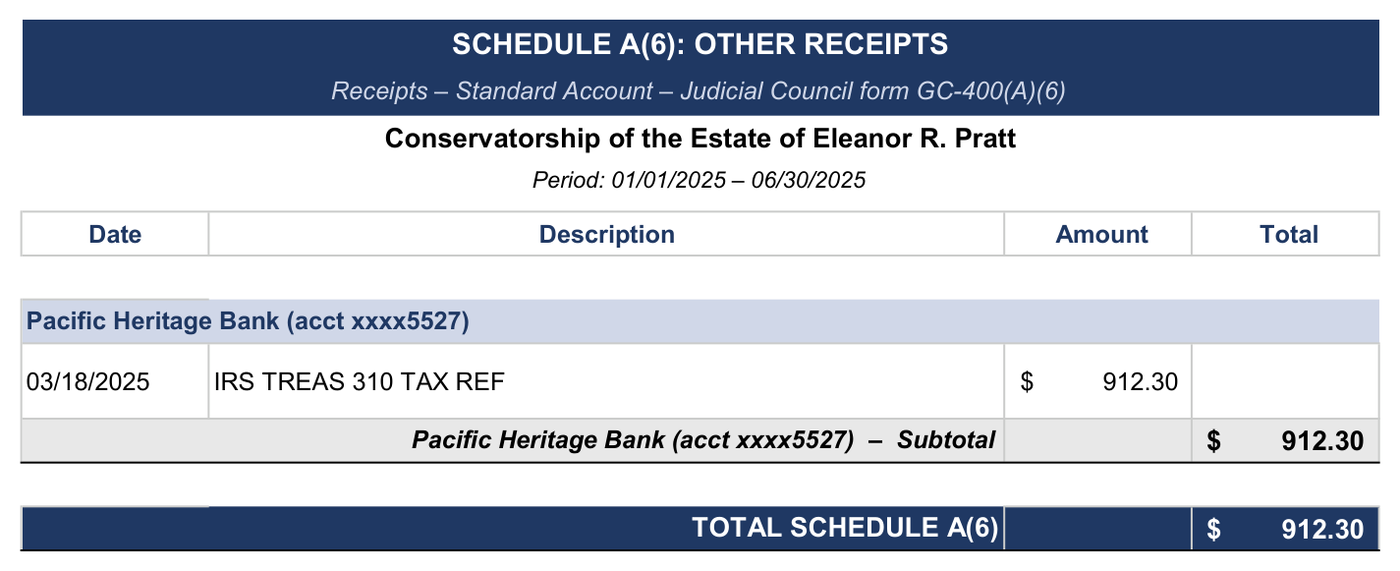
GC-400(A)(6): other receipts
Receipts that fit none of the categories above.
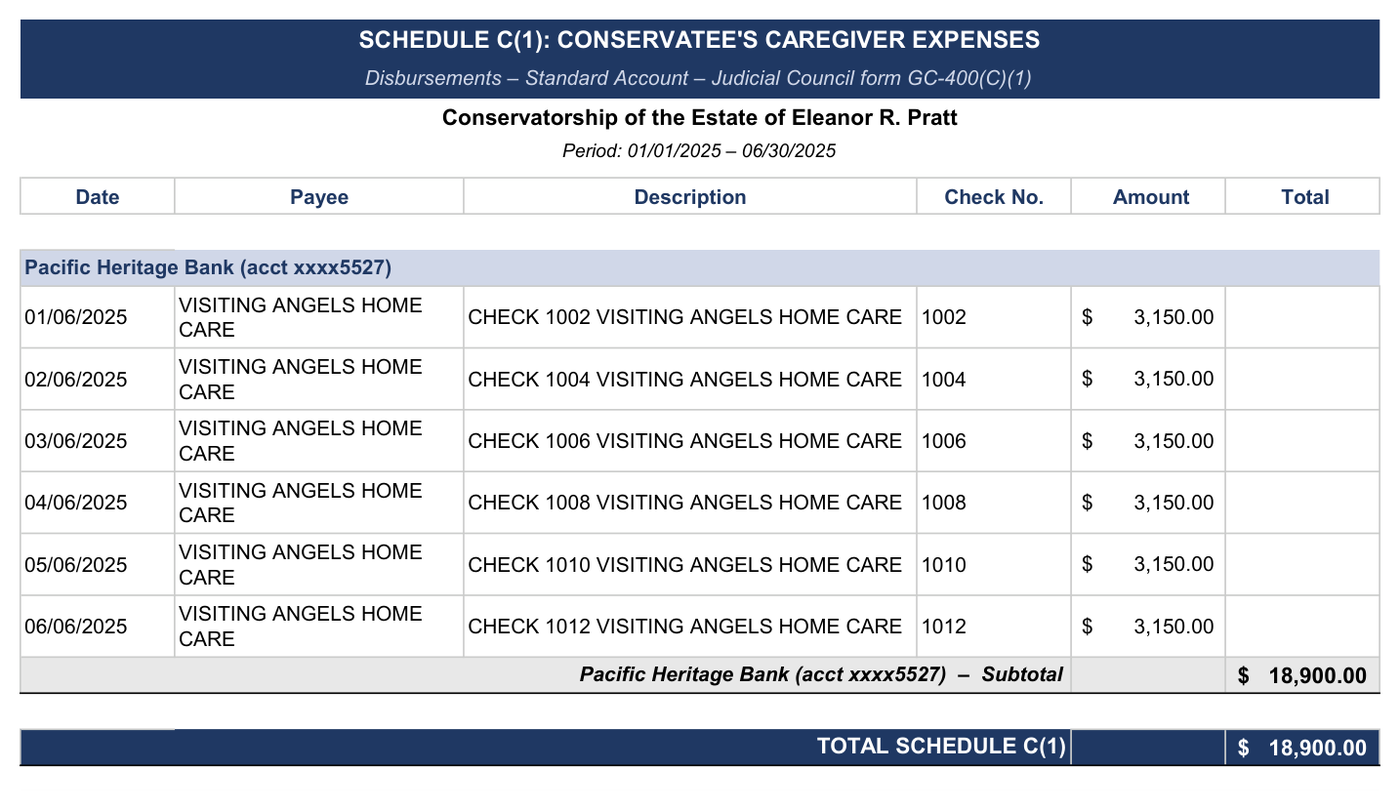
GC-400(C)(1): caregiver expenses
Each payment for the conservatee’s caregivers, with the check number.
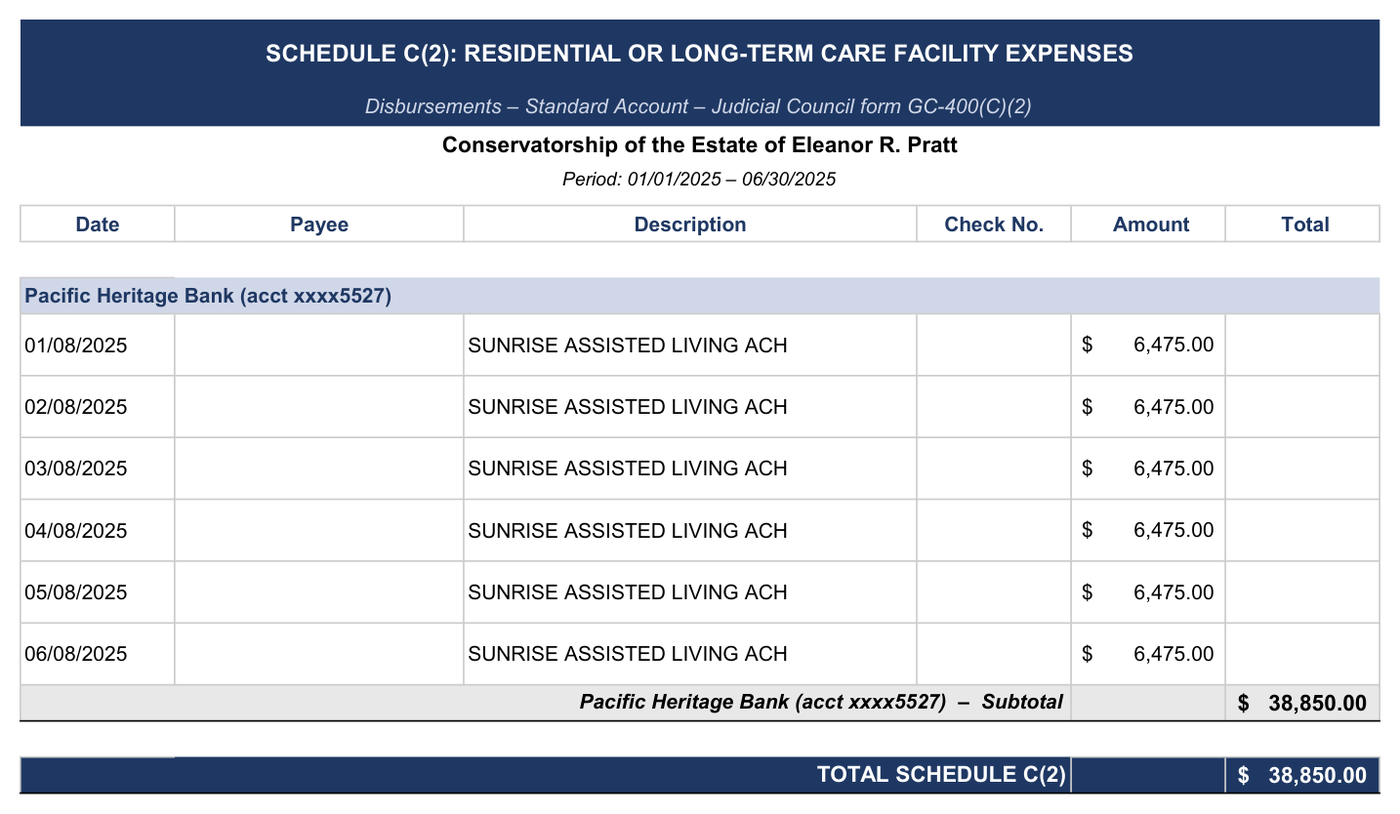
GC-400(C)(2): residential or long-term care facility
Each payment to a residential or long-term care facility.
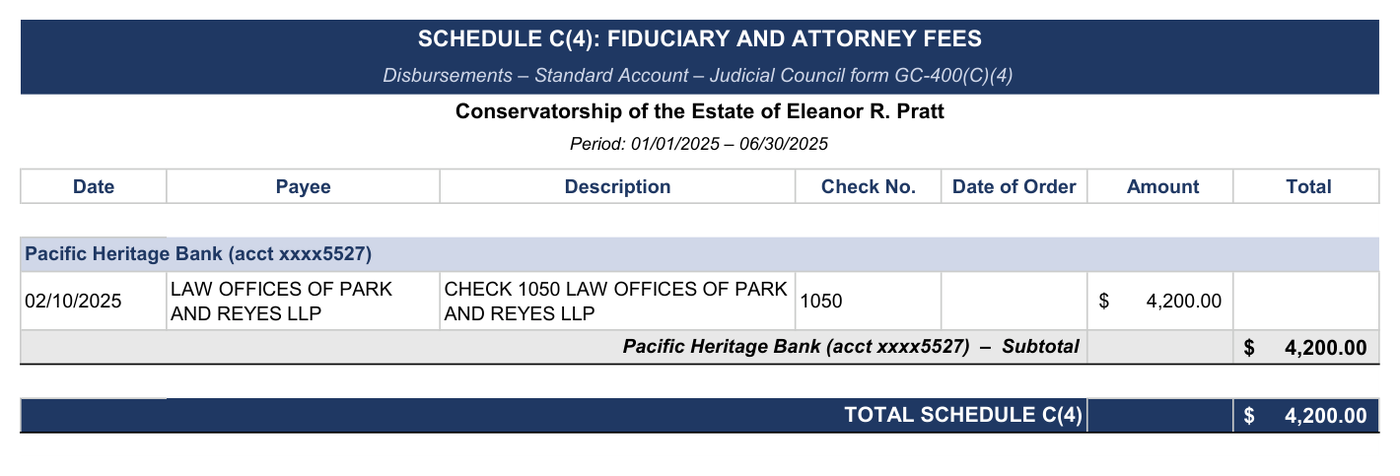
GC-400(C)(4): fiduciary and attorney fees
Each fee paid, with the date of the court order that authorized it.
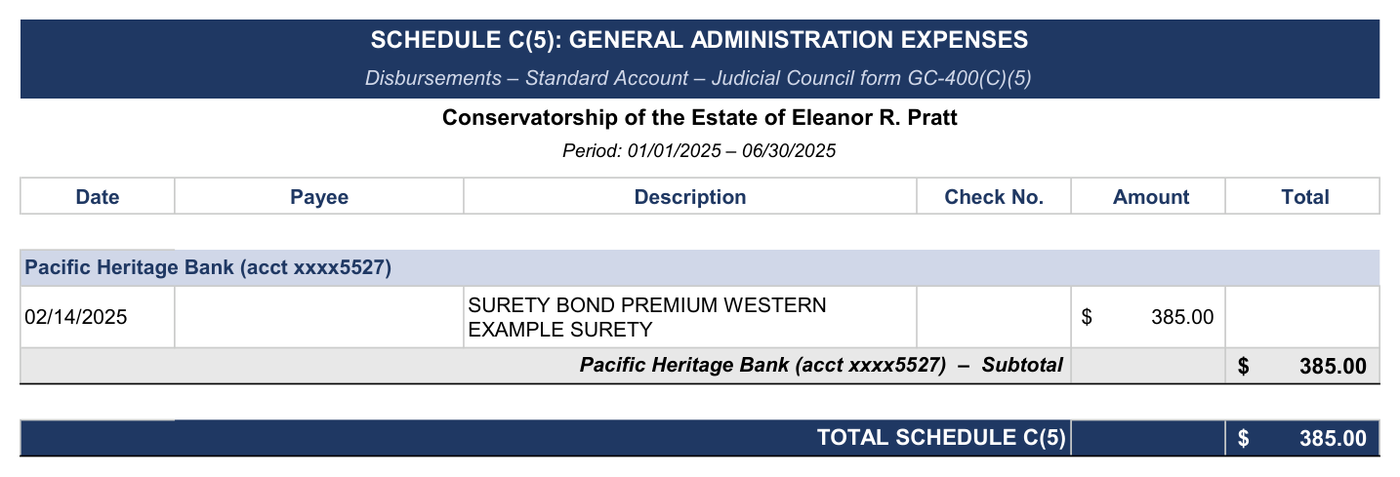
GC-400(C)(5): general administration expenses
Bond premiums, court costs and other administration expenses.
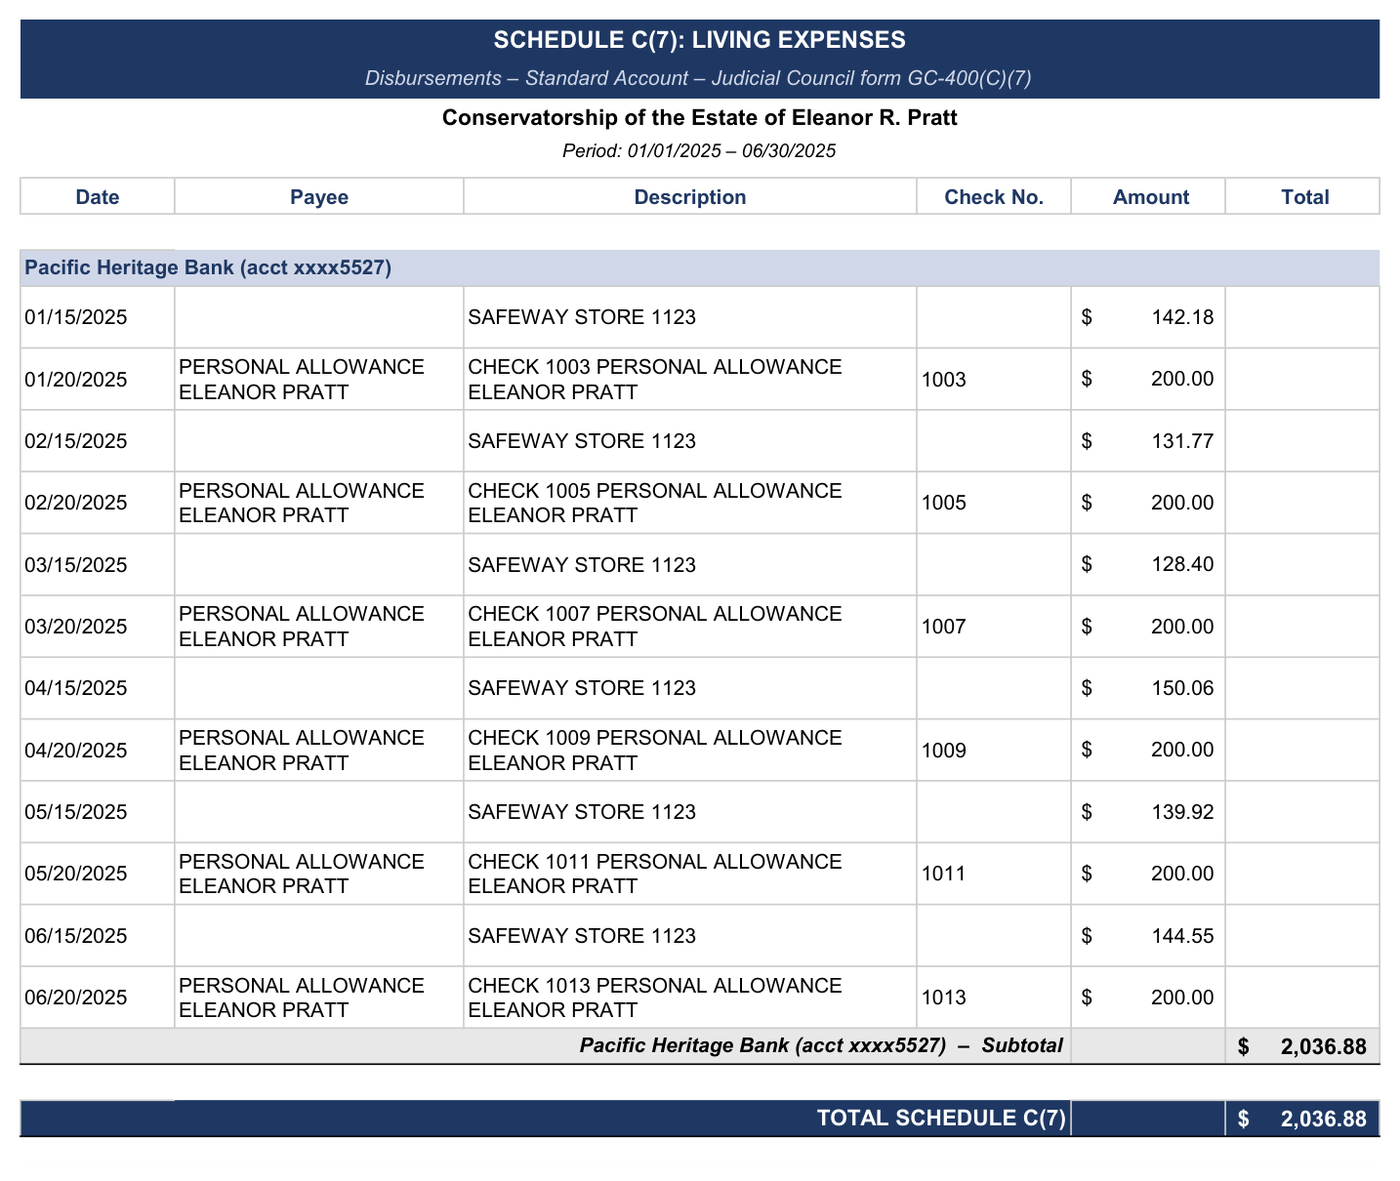
GC-400(C)(7): living expenses
Housing, food, utilities and other living expenses.
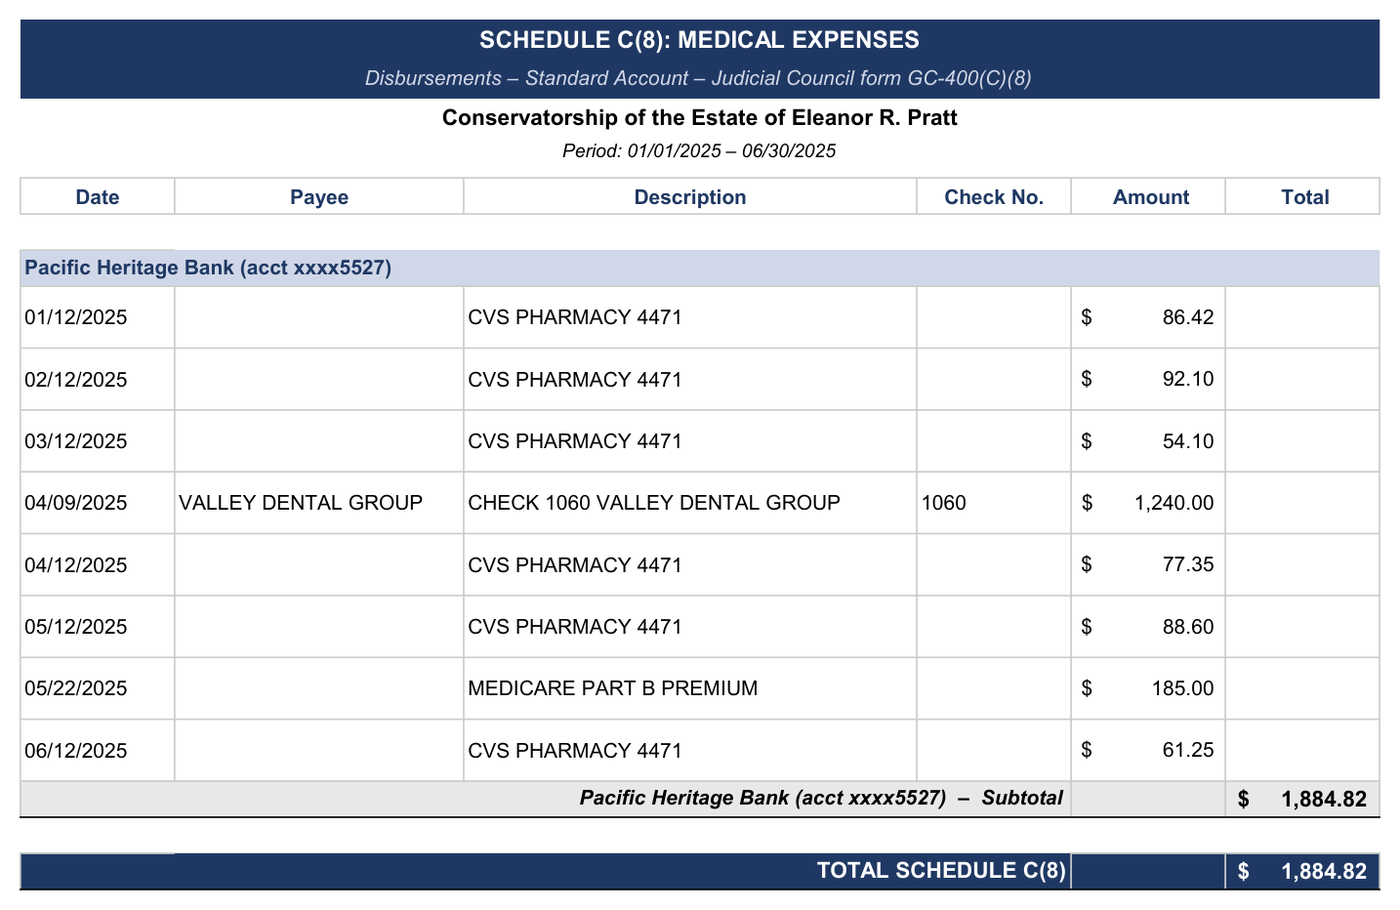
GC-400(C)(8): medical expenses
Doctors, pharmacies, insurance premiums and other medical expenses.
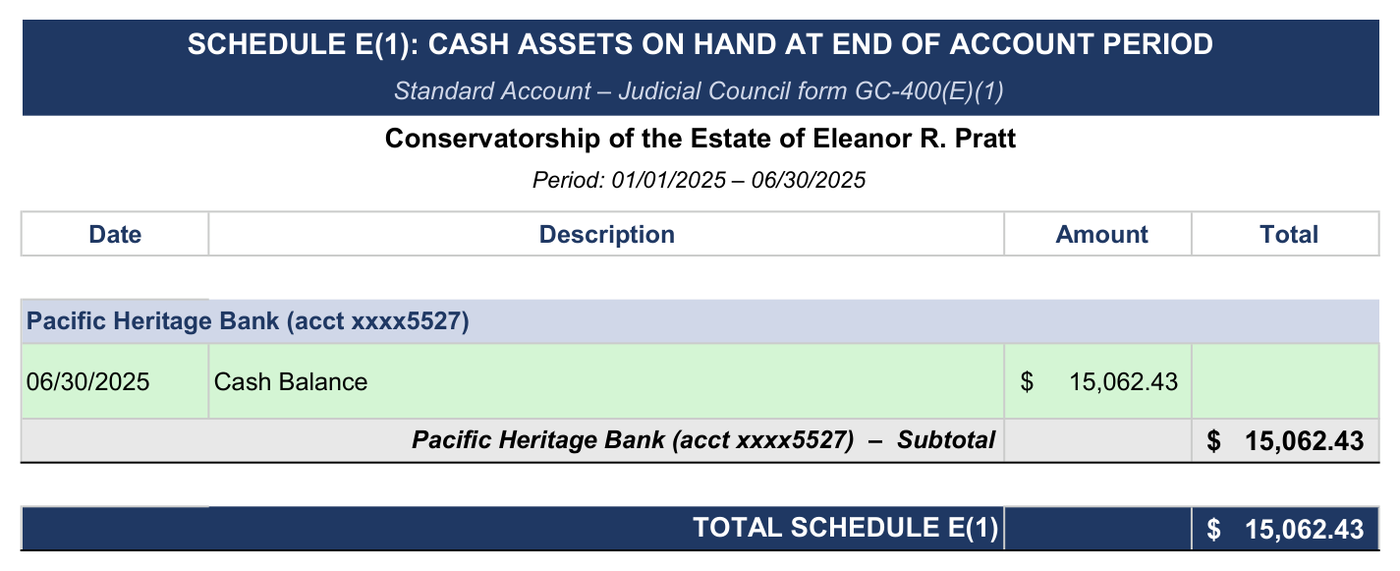
GC-400(E)(1): cash assets on hand at the end
Each account’s cash balance on the last day of the period.
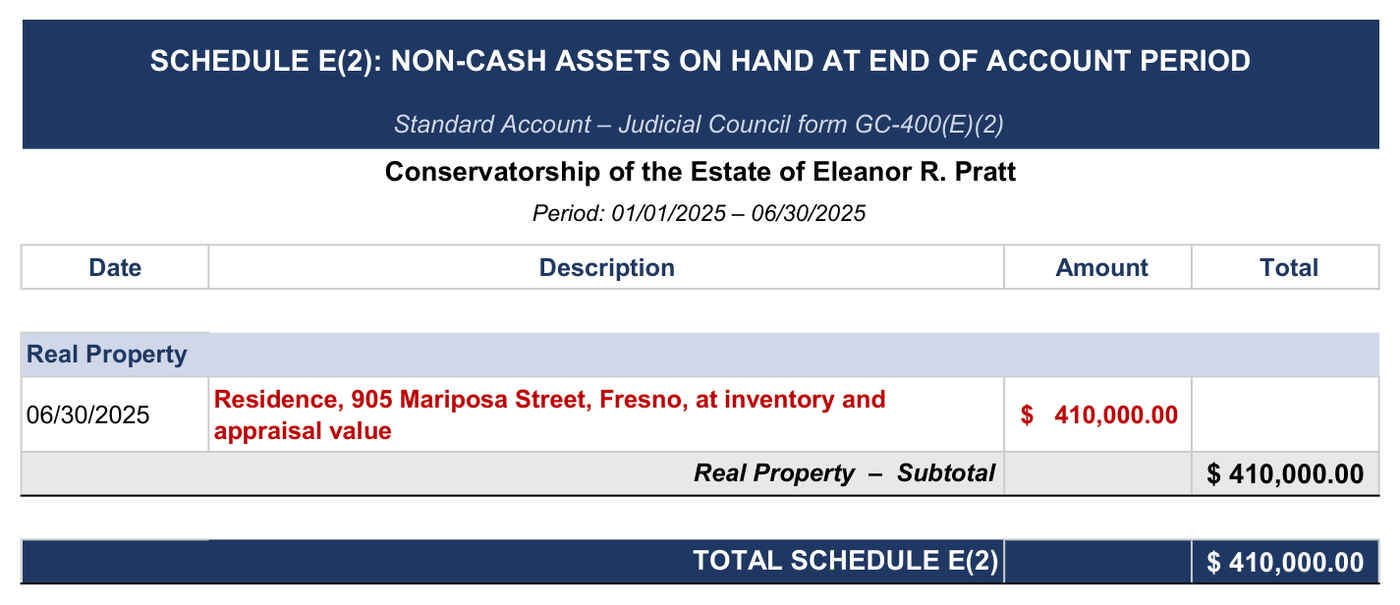
GC-400(E)(2): non-cash assets on hand at the end
Non-cash assets at the close of the period, at carry value.
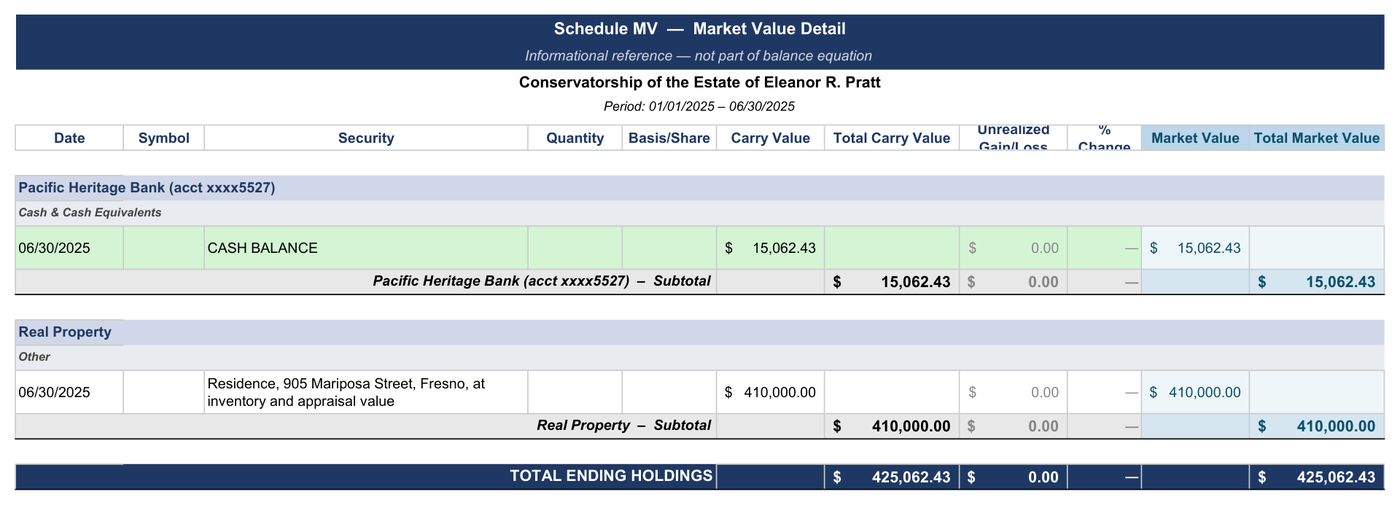
Market value at the end of the period
Each holding at carry value and at market value (§1063(a)). For reference; it is not part of the balance.
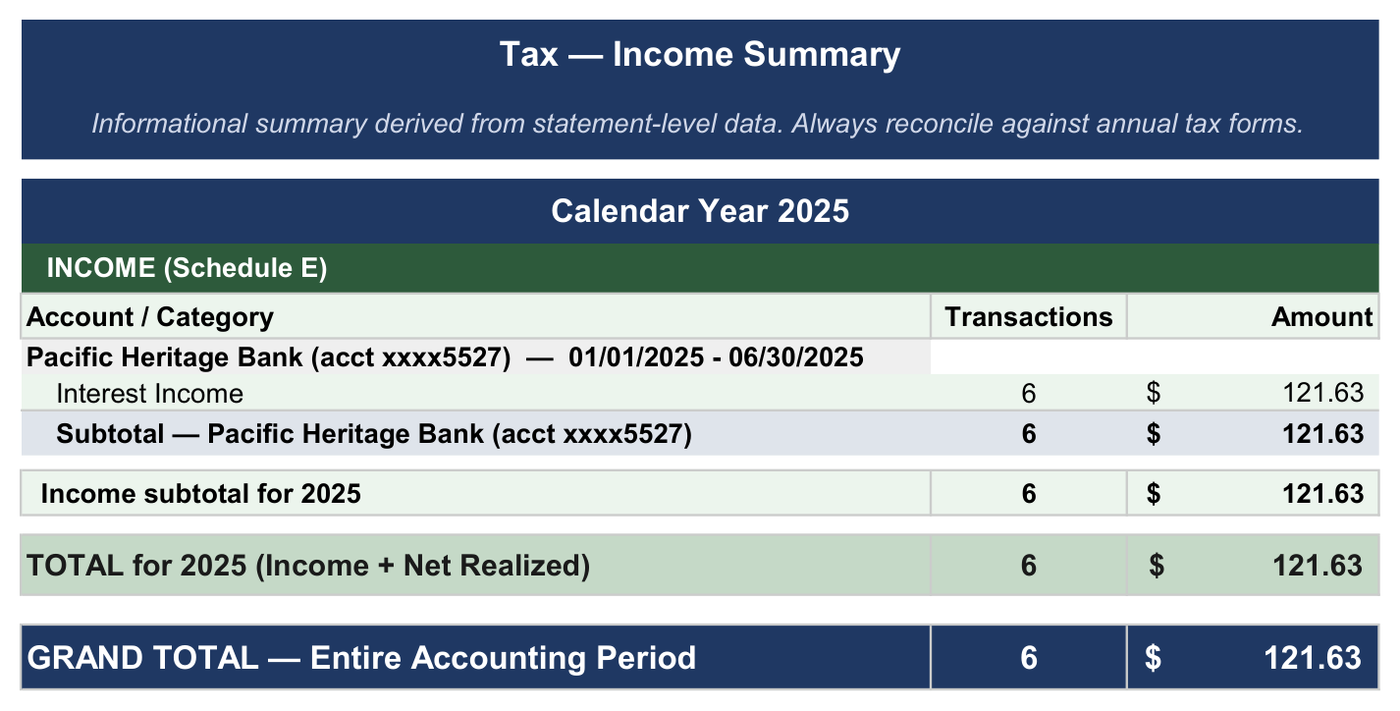
Tax summary for the CPA
Income and realized gains and losses by calendar year and account. For the fiduciary income tax return; not part of the accounting.
Generate yours
Balanced generates an accounting of this kind from the fiduciary’s PDF bank and brokerage statements: transactions classified to their schedules, carry values tracked lot by lot, each account reconciled to its own statements, the summary balanced to the penny, and each entry cited to the statement and page from which it was drawn, delivered as the GC-400 layout, in one fully editable Excel workbook for review and verification. $699 per accounting.
Prefer to fill it in yourself? Use the free GC-400 accounting template. More on GC-400 accountings.