A complete estate accounting, schedule by schedule
This is a complete sample account for a fictional decedent’s estate, the Estate of Harold J. Whitcomb, generated by Balanced in the format of a California probate court accounting, the format a final accounting for probate court follows. It covers six months of administration, including the sale of the residence, creditor claims, a specific gift, interest on a general pecuniary gift and the statutory fee computation. The estate, the people and the account numbers are made up. Click any schedule to see the whole sheet.
Download the sample accounting (PDF)
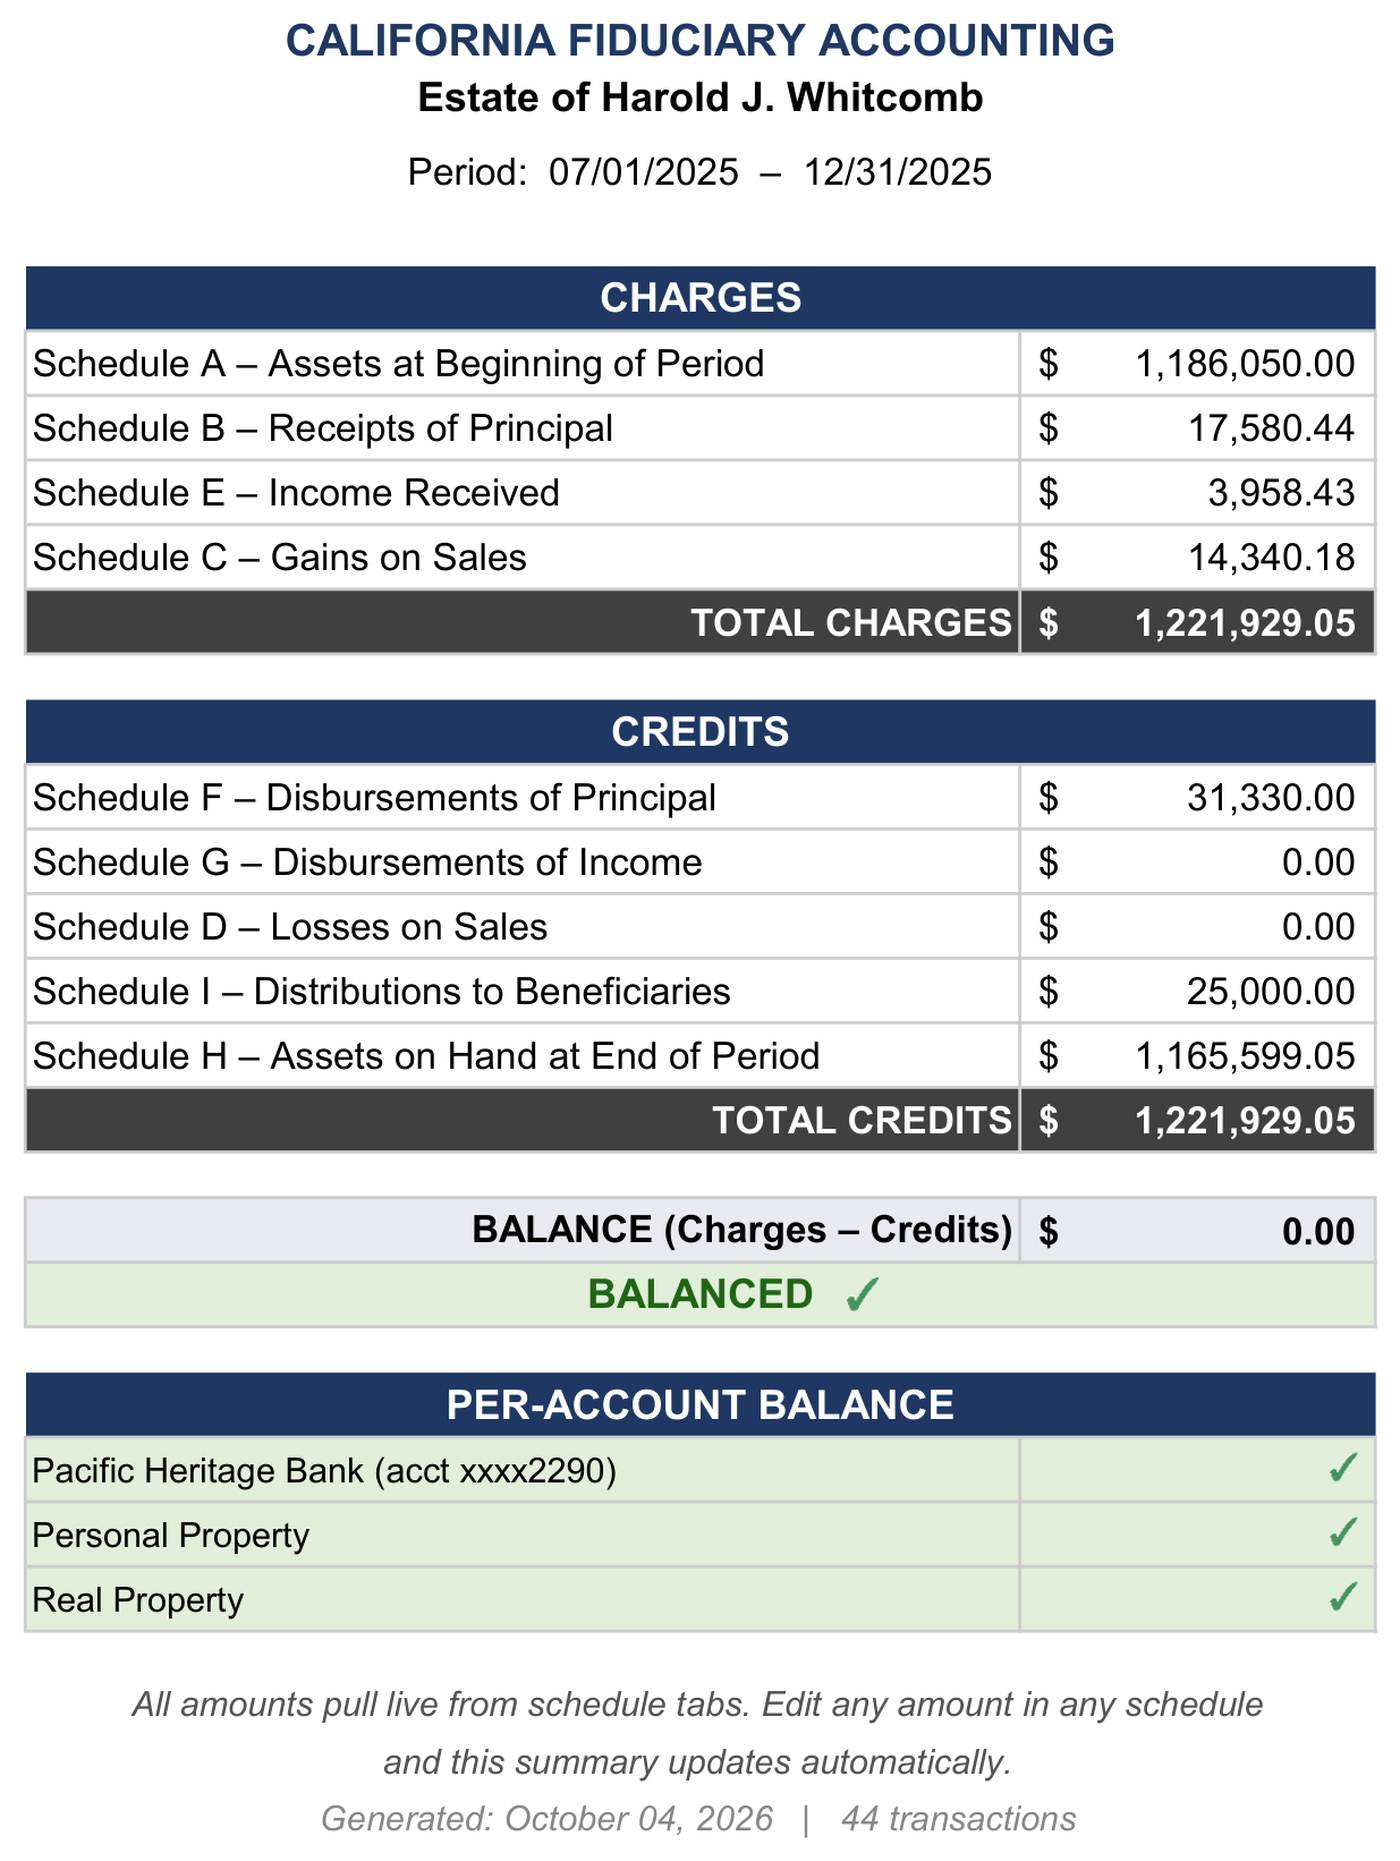
The summary of account
The charges (what the fiduciary started with and received) against the credits (what was paid out, distributed or is still on hand). Under Probate Code §1061(c) the two totals must be equal; the balance line shows zero. Each line pulls its total from its schedule.
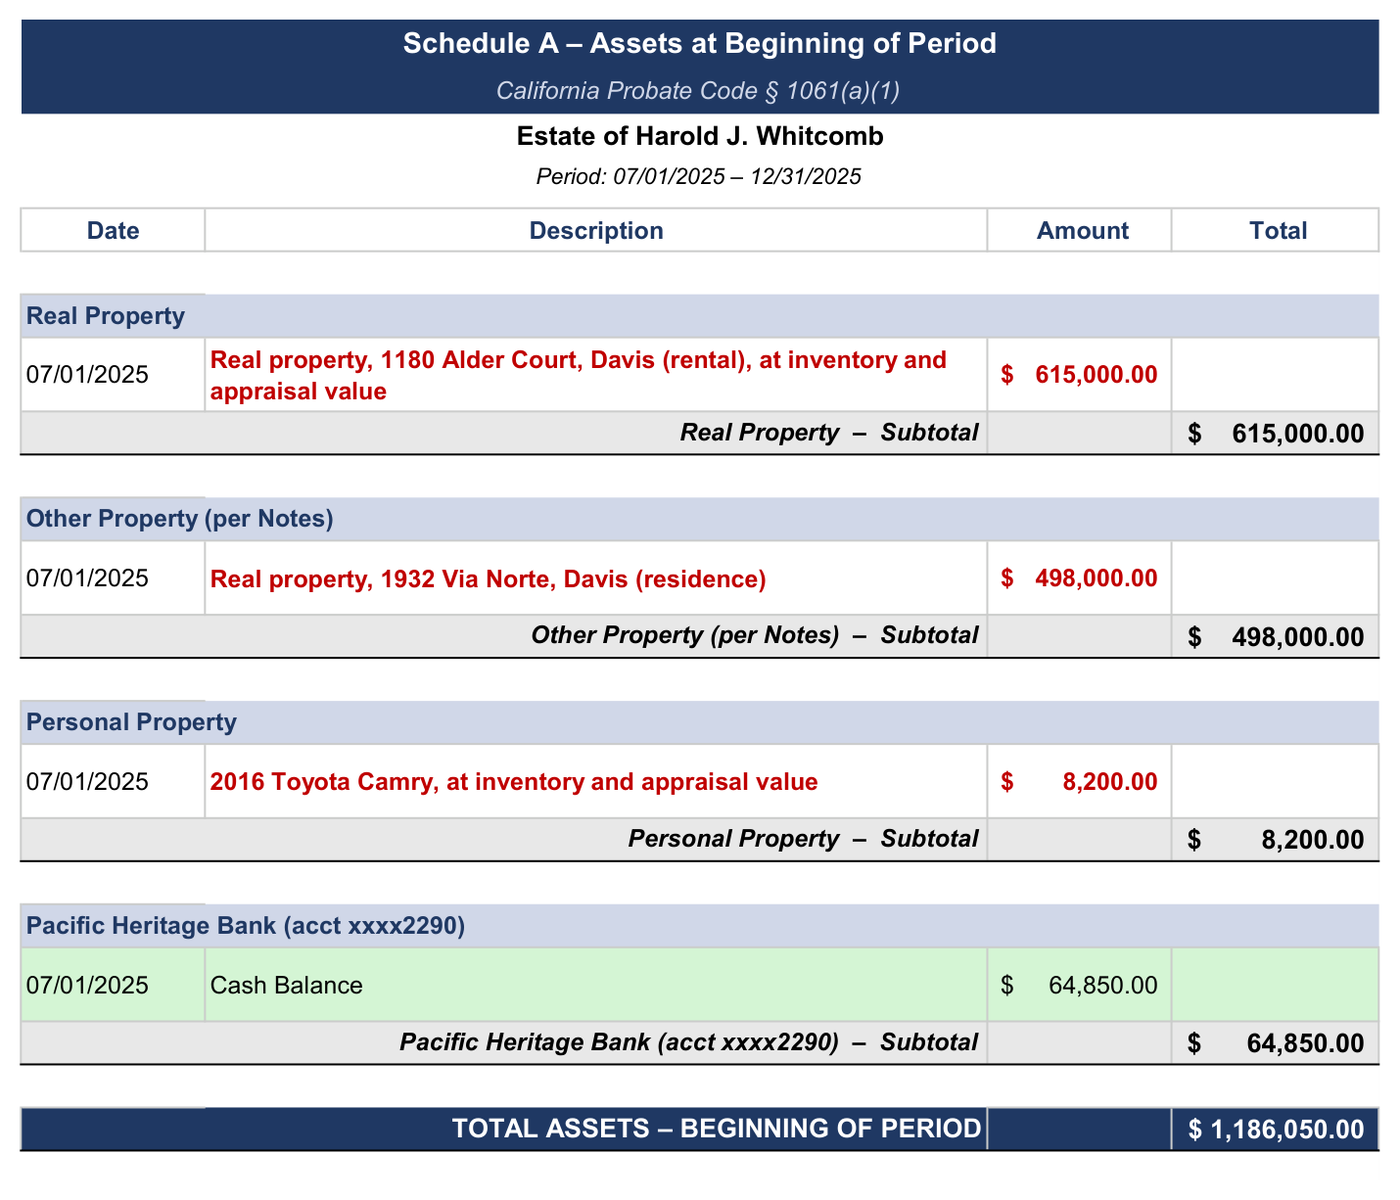
Schedule A: property on hand at the beginning
Every asset on hand on the first day of the period, account by account, at carry value (§1061(a)(1)). For a later account it is the prior account’s Schedule H.
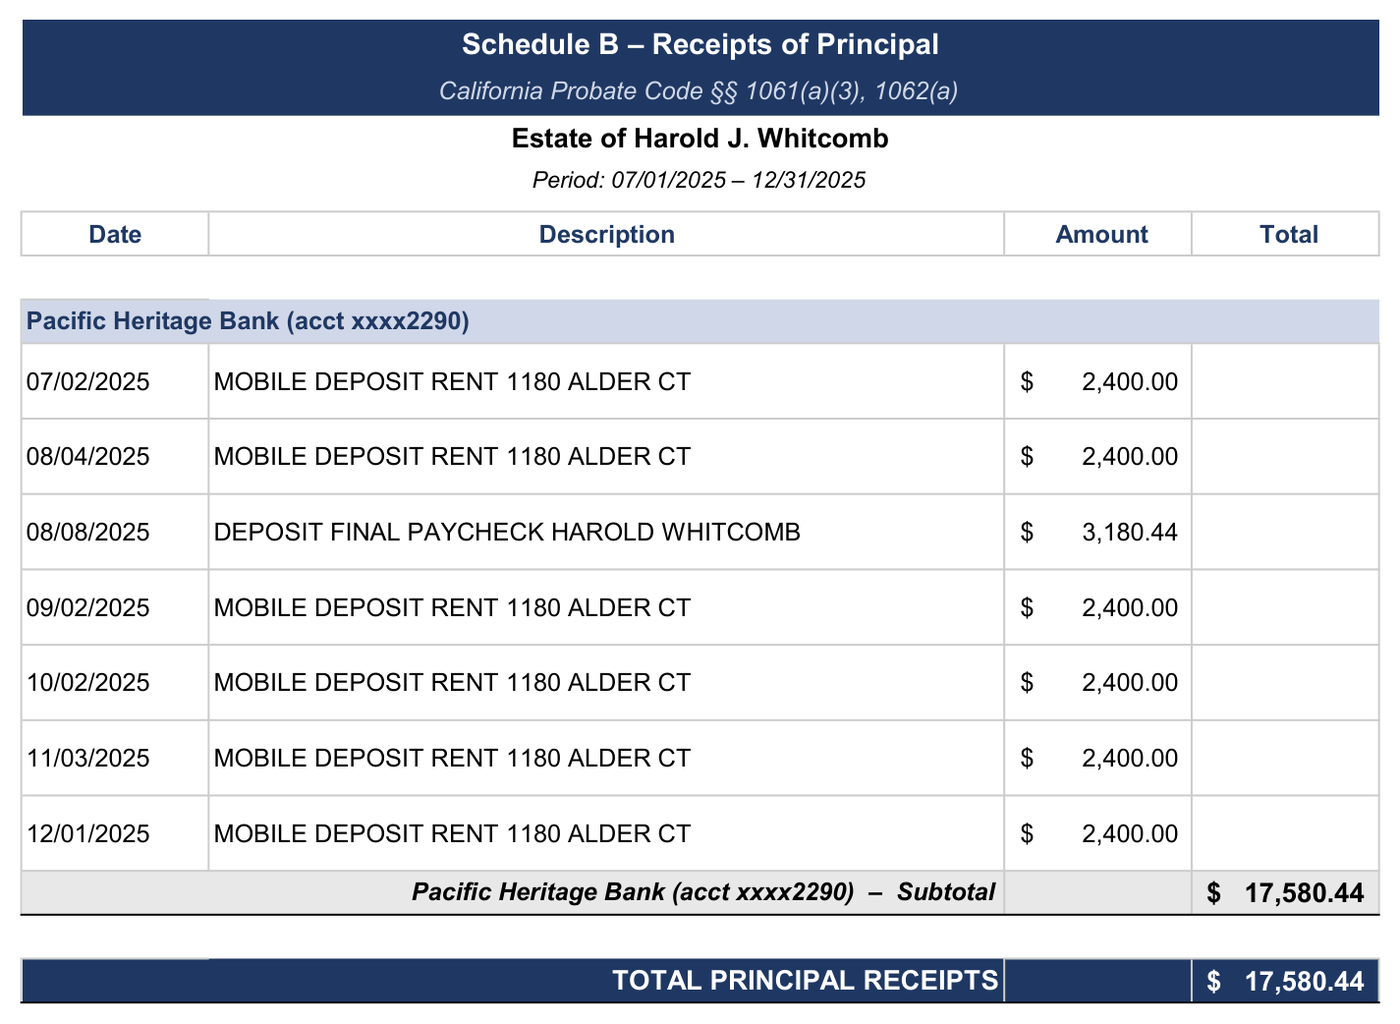
Schedule B: receipts of principal
Each receipt of principal with its nature or purpose, source and date (§§1061(a)(3), 1062(a)).
Schedule E: income received
Each dividend, interest payment and other income receipt, with its source and date (§§1061(a)(3), 1062(a)).
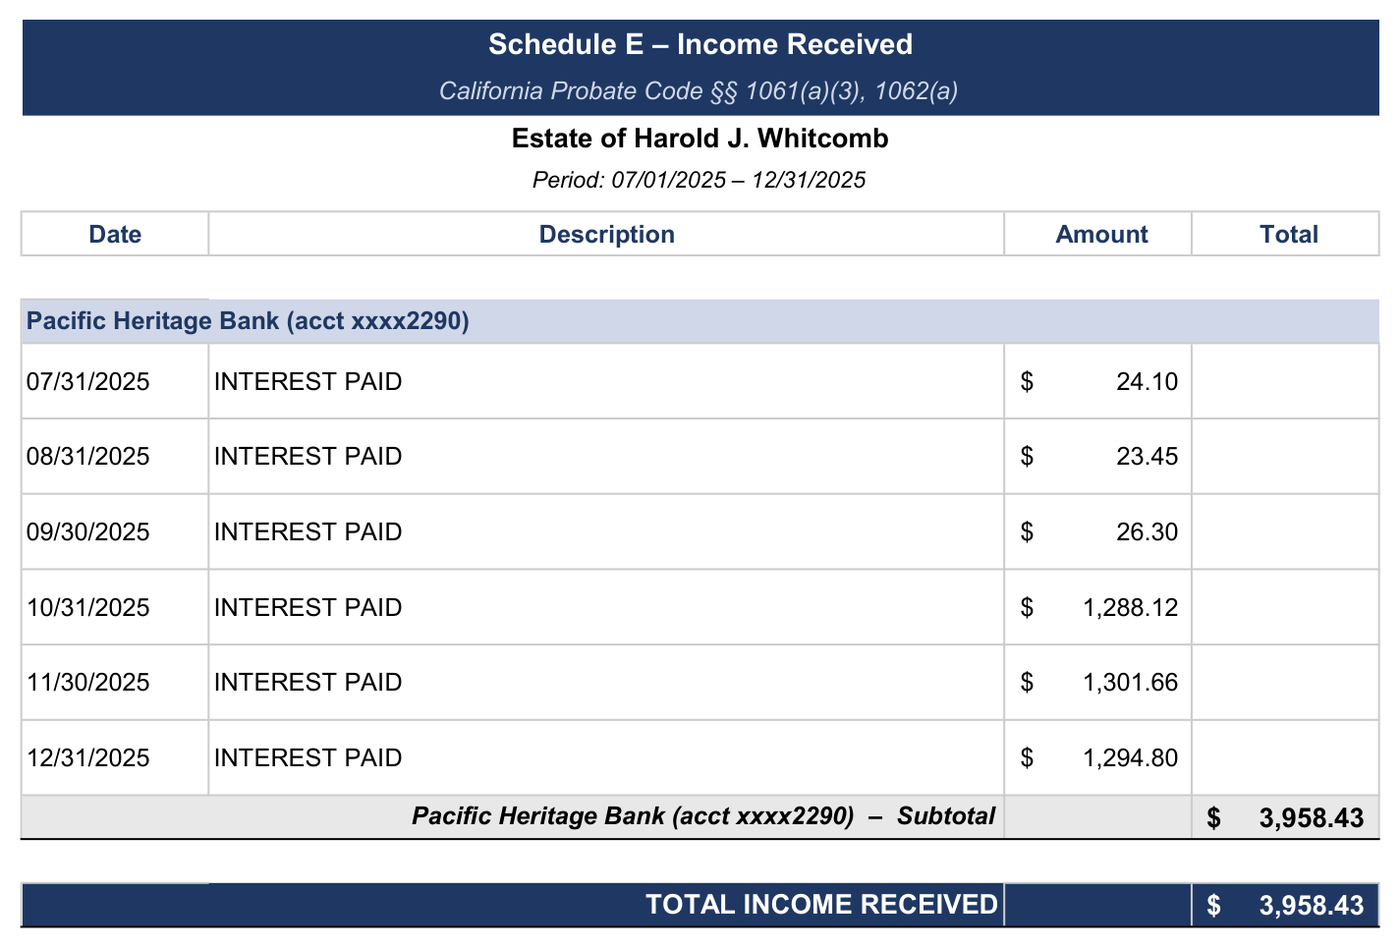
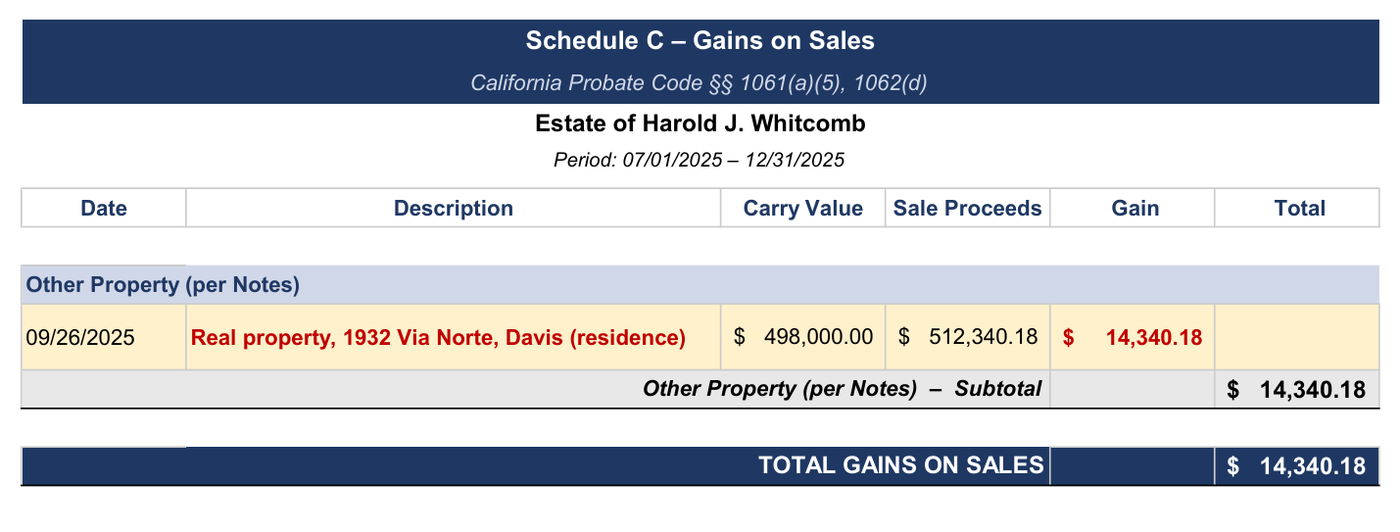
Schedule C: gains on sales
Each sale or other disposition that produced a gain, calculated from carry value (§§1061(a)(5), 1062(d)).
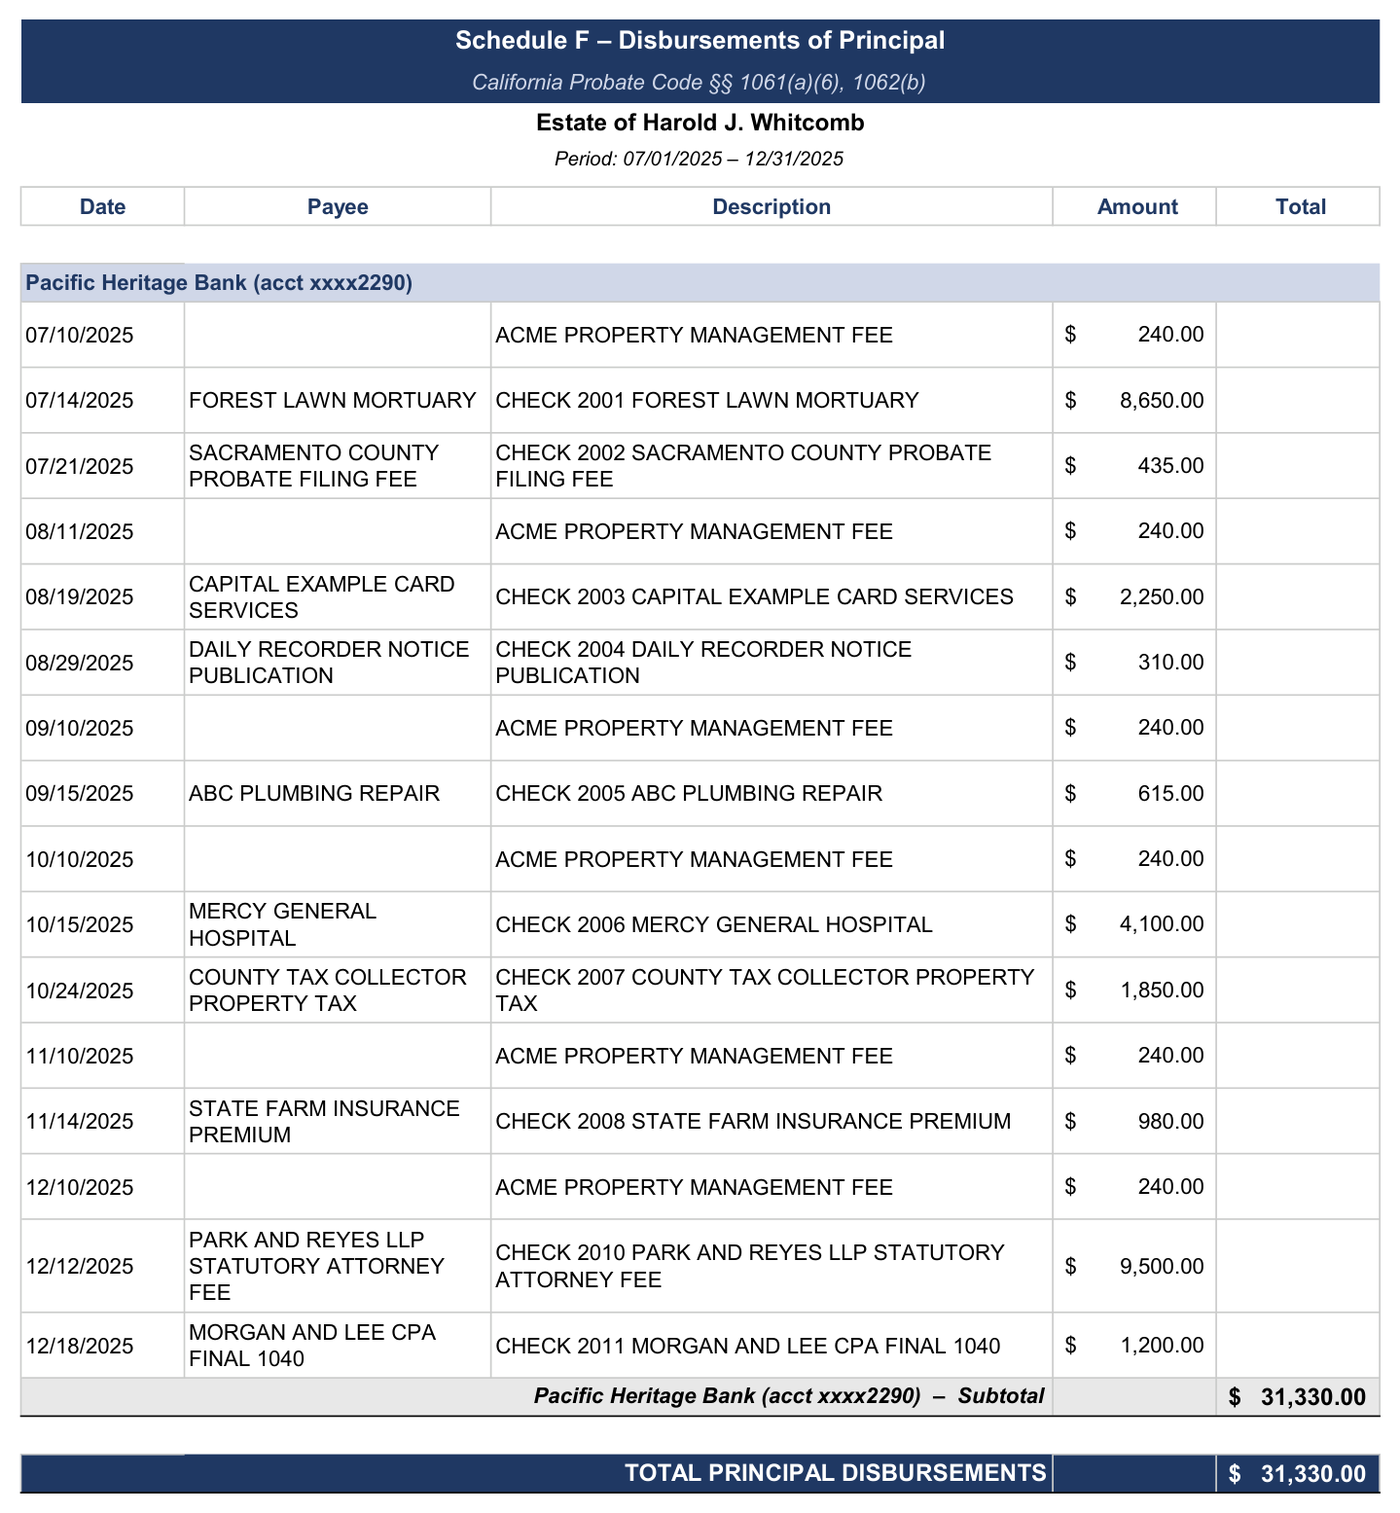
Schedule F: disbursements of principal
Each disbursement with its nature or purpose, payee and date (§§1061(a)(6), 1062(b)).
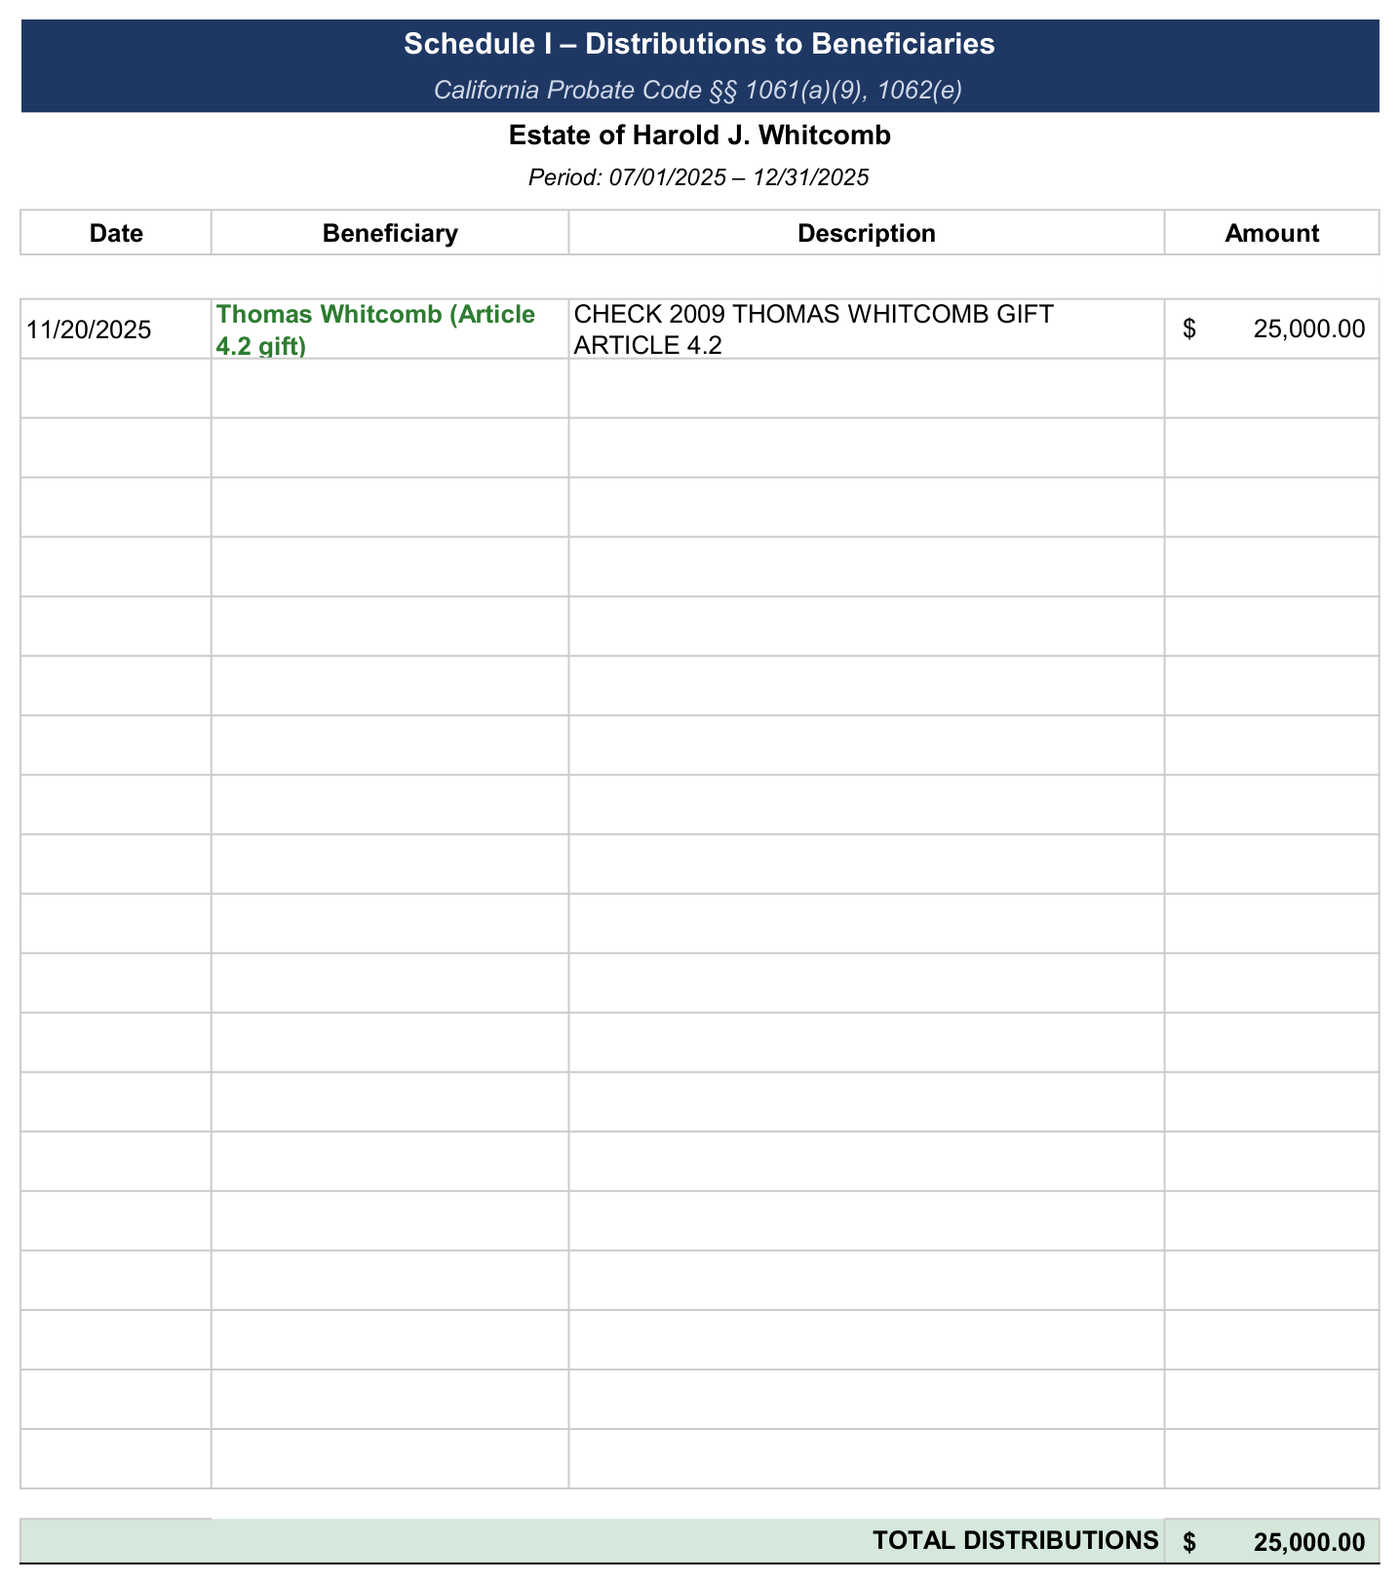
Schedule I: distributions
Each distribution of cash or property to a beneficiary, with the date and amount, property at carry value (§§1061(a)(9), 1062(e)).
Schedule G: disbursements of income
Disbursements charged to income rather than principal, with the same detail (§§1061(a)(6), 1062(b)).
Schedule D: losses on sales
Each sale or other disposition that produced a loss, calculated from carry value (§§1061(a)(7), 1062(d)).
Schedule H: property on hand at the end
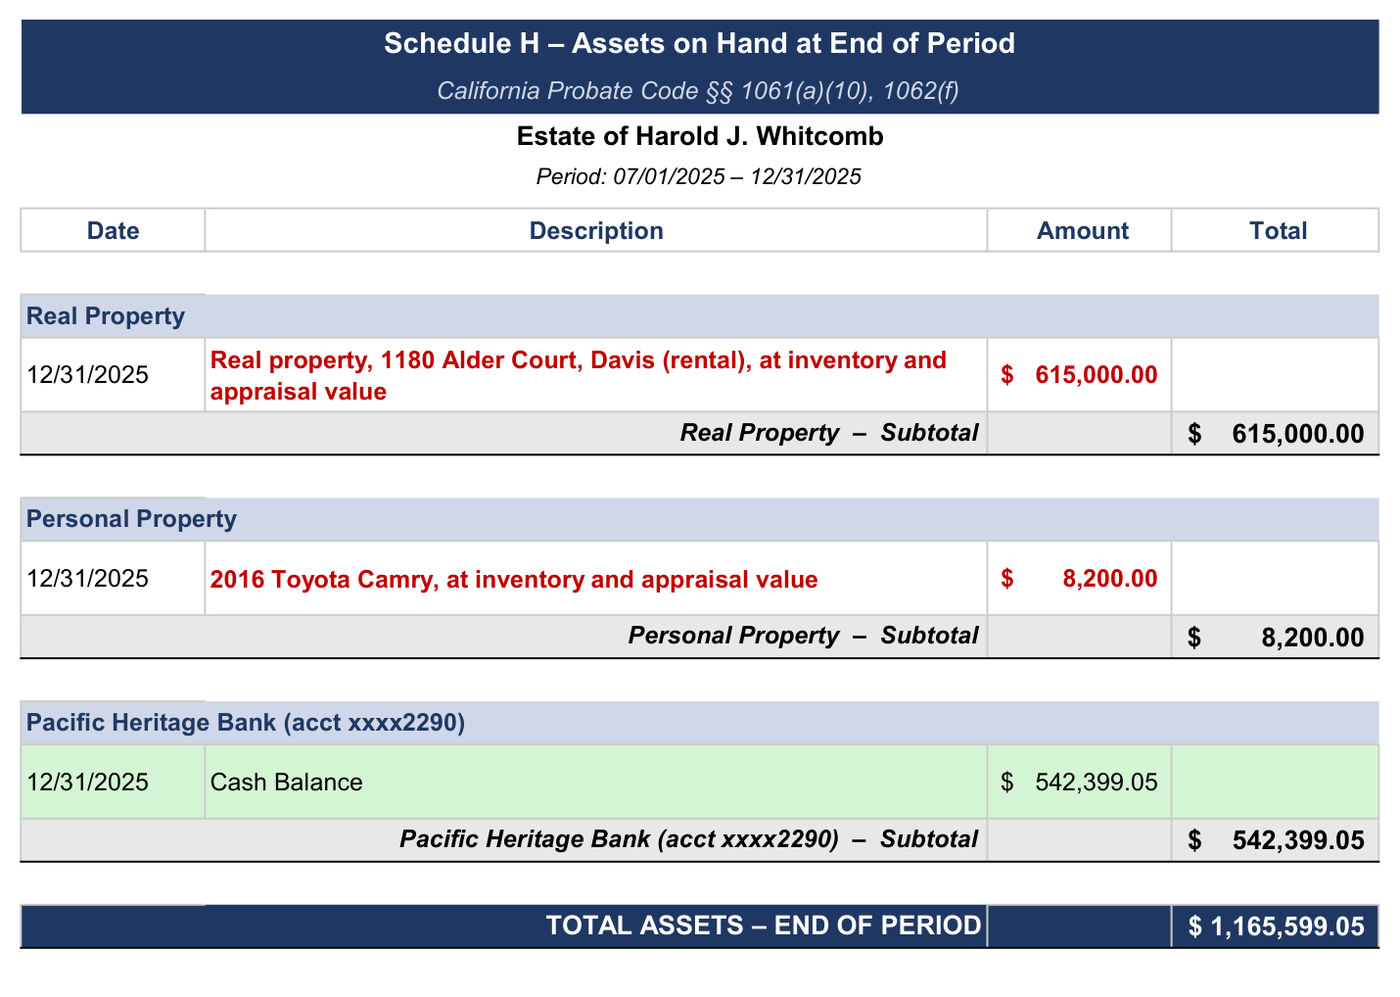
An itemized list of the property on hand at the close of the period, at carry value (§§1061(a)(10), 1062(f)). It becomes Schedule A of the next account.
Market value at the end of the period
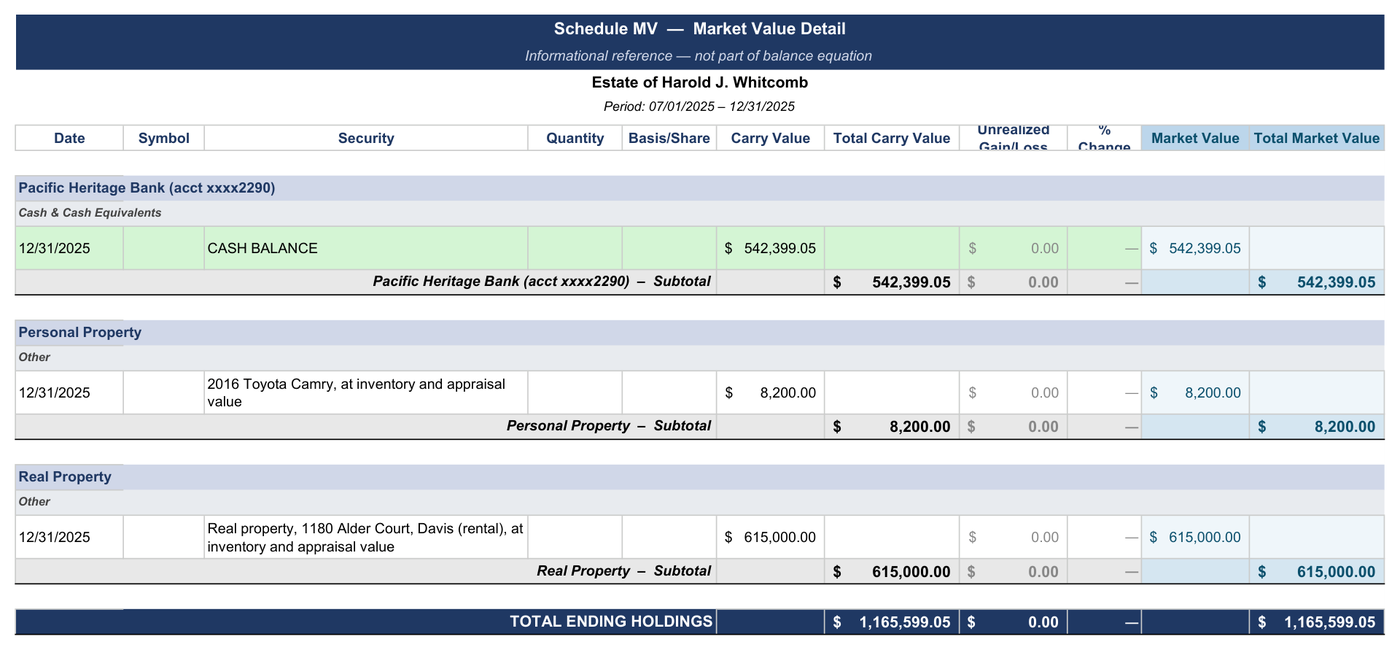
Each holding at carry value and at market value (§1063(a)). For reference; it is not part of the balance.
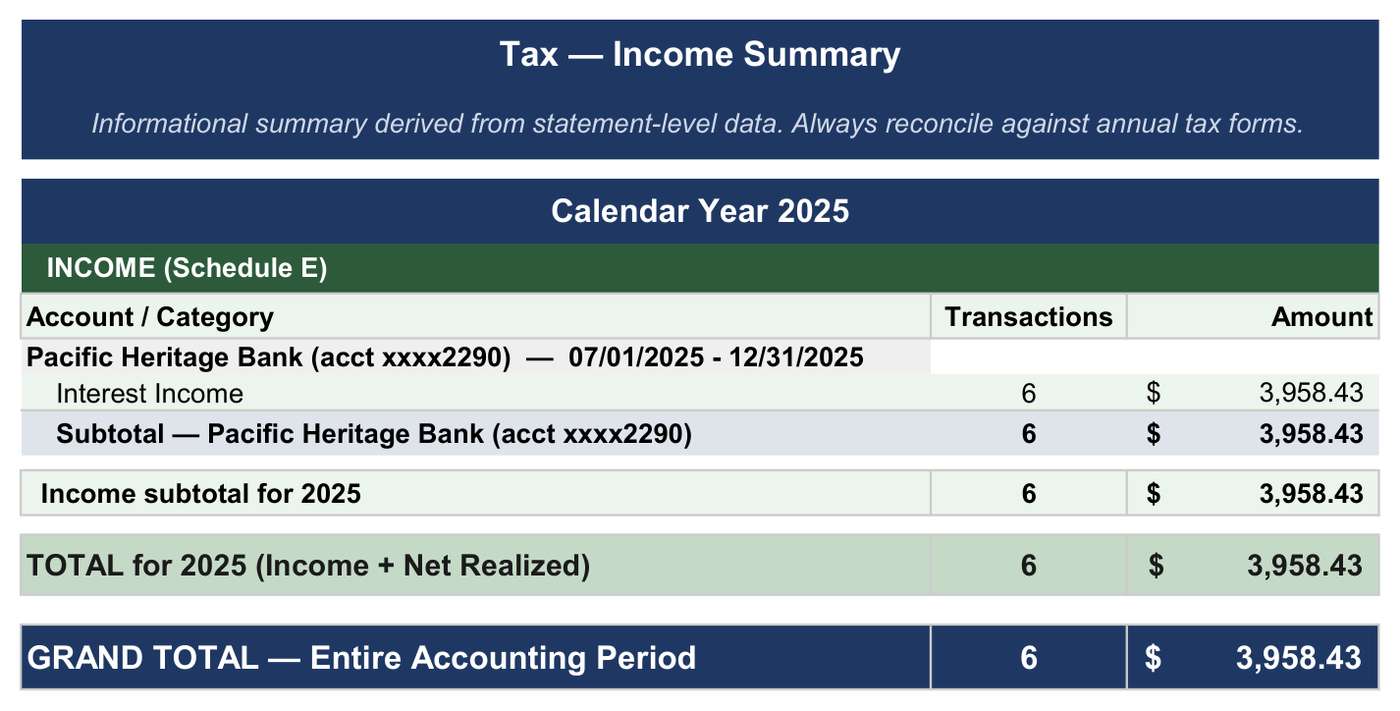
Tax summary for the CPA
Income and realized gains and losses by calendar year and account. For the fiduciary income tax return; not part of the accounting.
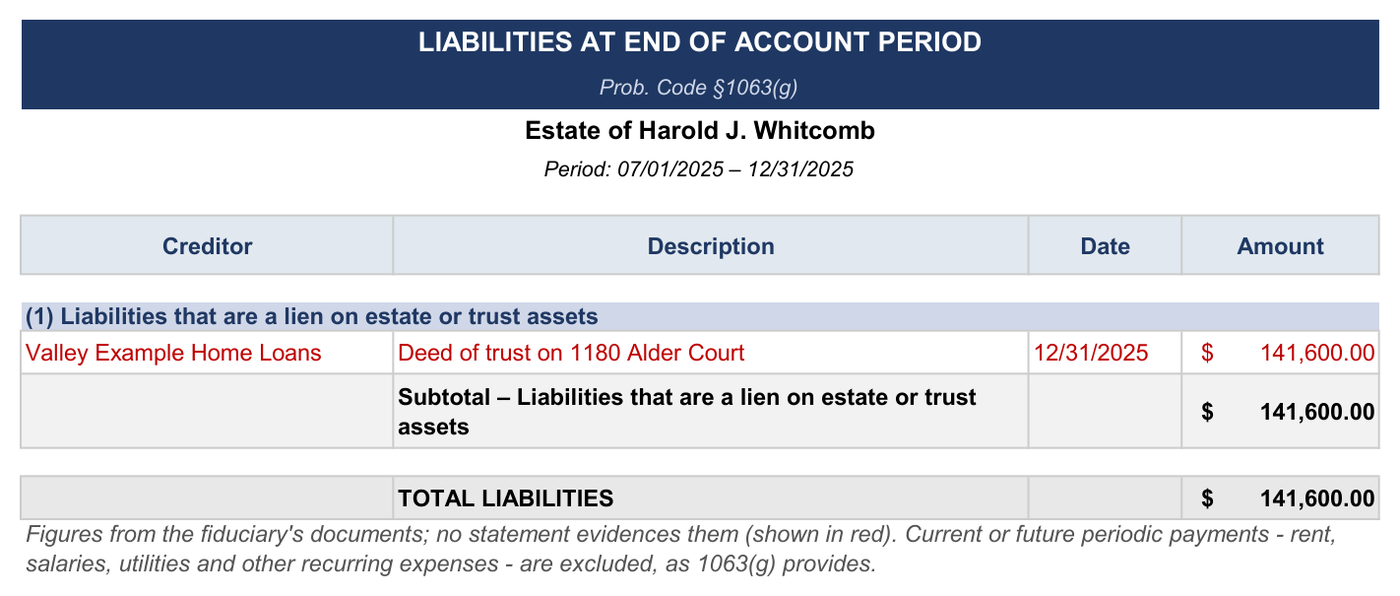
Liabilities
The liabilities of the trust or estate at the end of the period, such as liens, unpaid taxes and notes (§1063(g)).
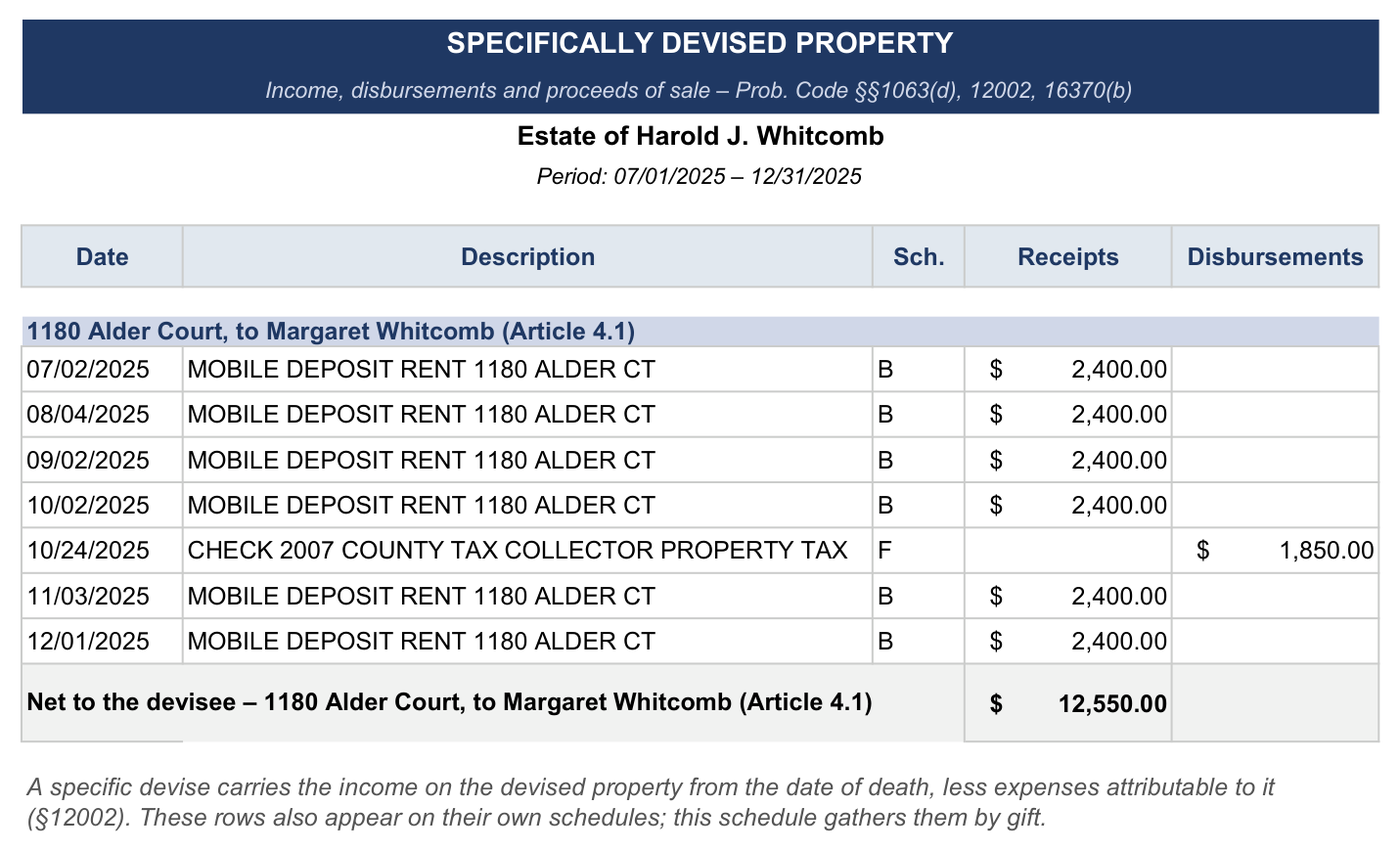
Specifically devised property
Income, disbursements and proceeds of sale of property specifically given by the will (§1063(d)).
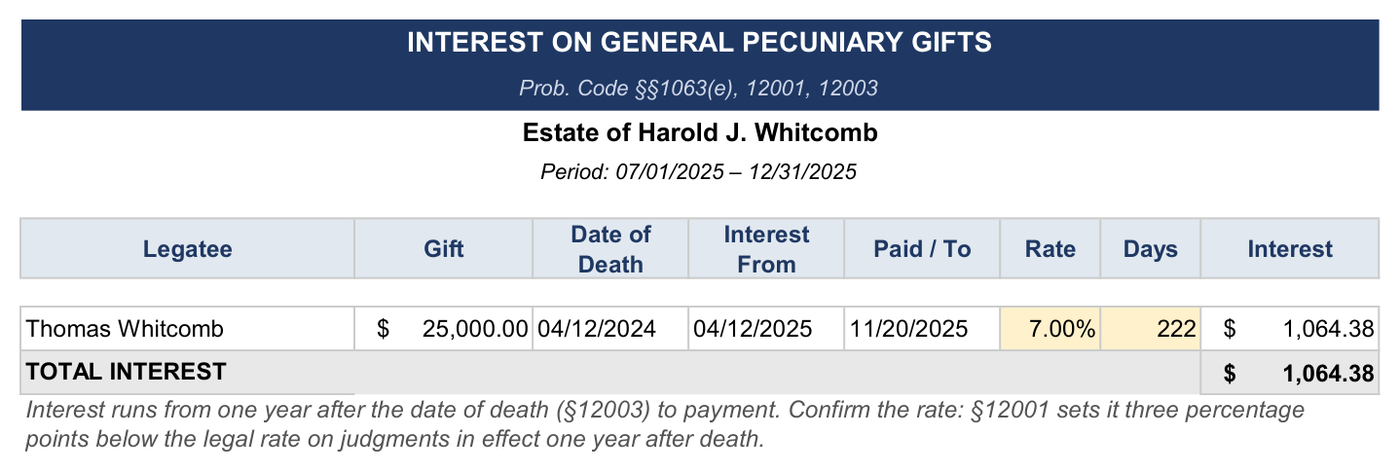
Interest on general pecuniary gifts
The calculation of interest on cash gifts not paid within a year after death (§§1063(e), 12001, 12003).
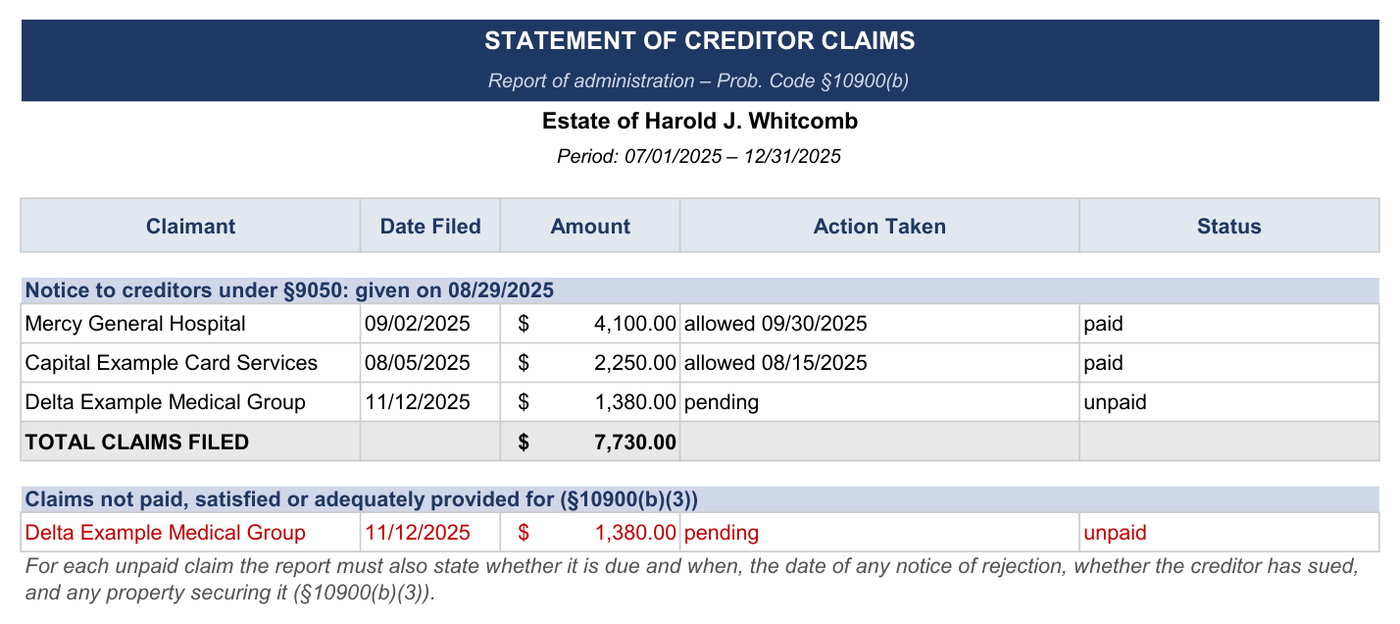
Creditor claims
Each claim filed, the action taken, and the claims not yet paid (report of administration, §10900(b)).
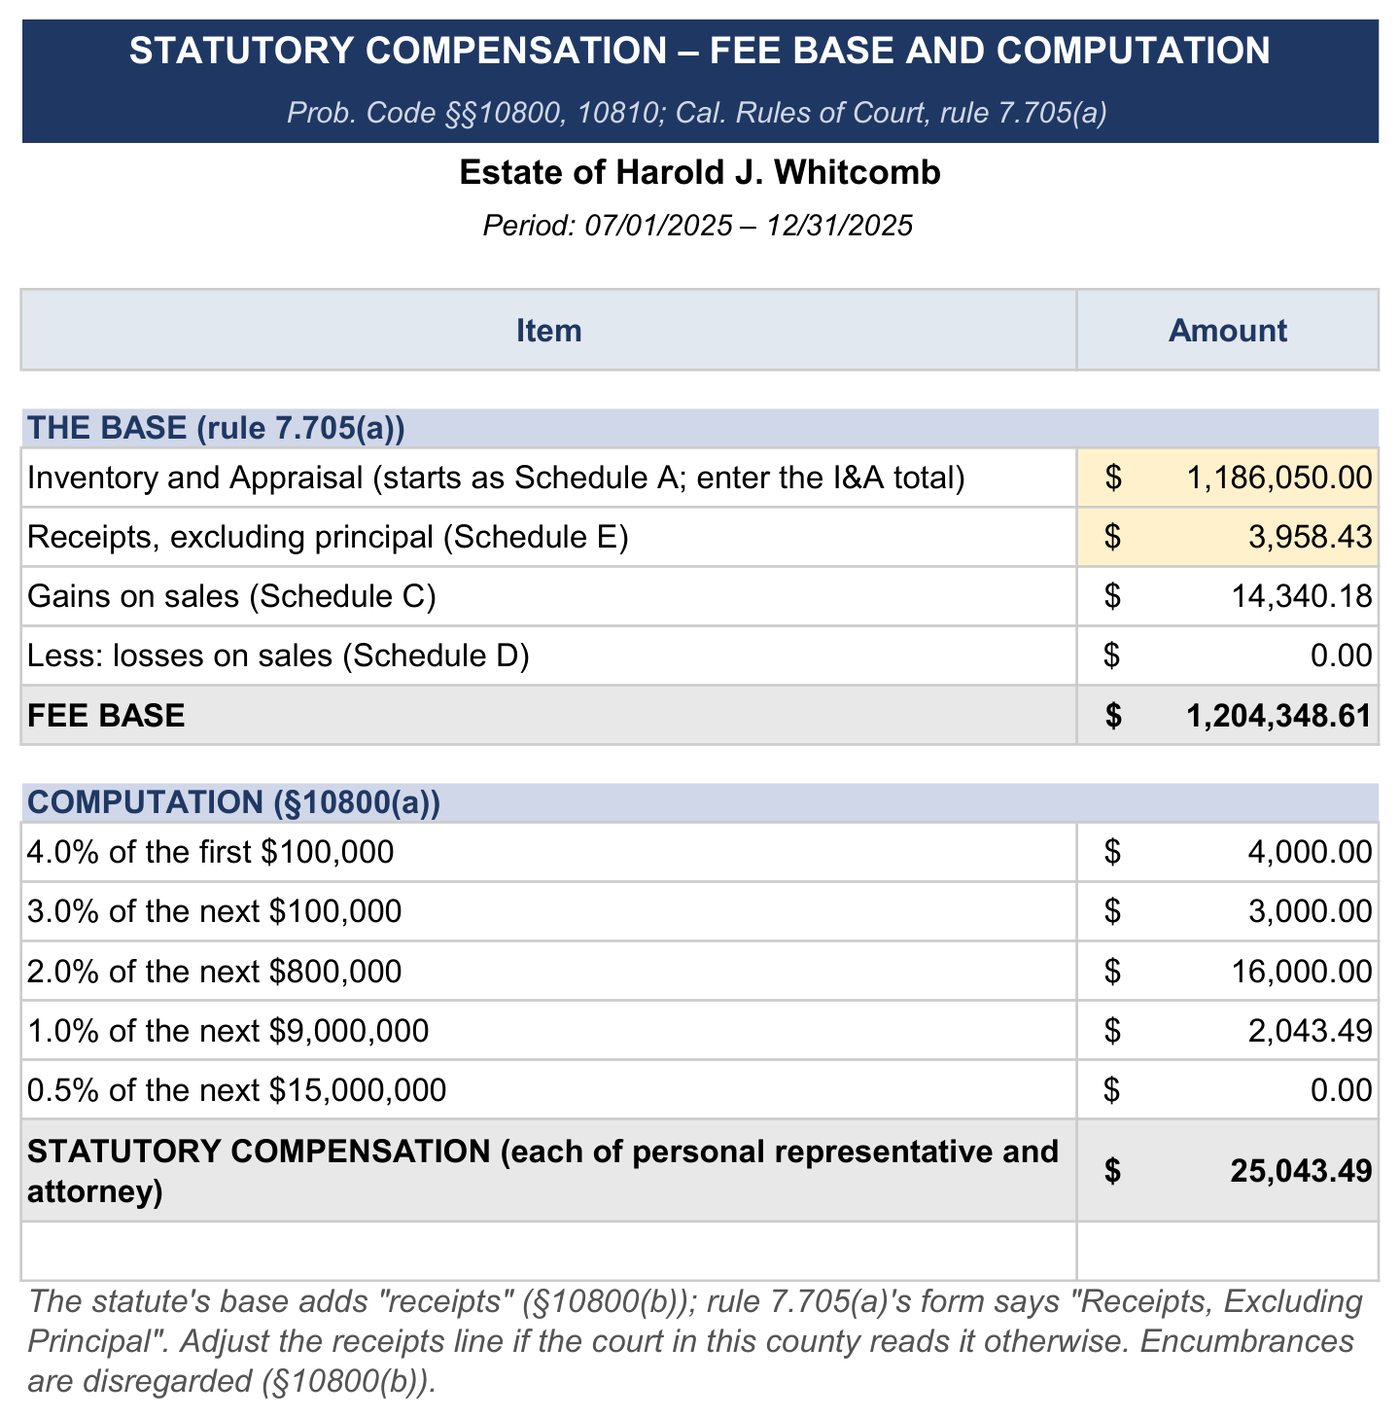
Statutory compensation
The fee base and the computation of the personal representative’s and attorney’s statutory compensation (§§10800, 10810; rule 7.705(a)).
Generate yours
Balanced generates an accounting of this kind from the fiduciary’s PDF bank and brokerage statements: transactions classified to their schedules, carry values tracked lot by lot, each account reconciled to its own statements, the summary balanced to the penny, and each entry cited to the statement and page from which it was drawn, delivered as one fully editable Excel workbook for review and verification. $699 per accounting.
Prefer to fill it in yourself? Use the free California accounting template, which follows the same format.